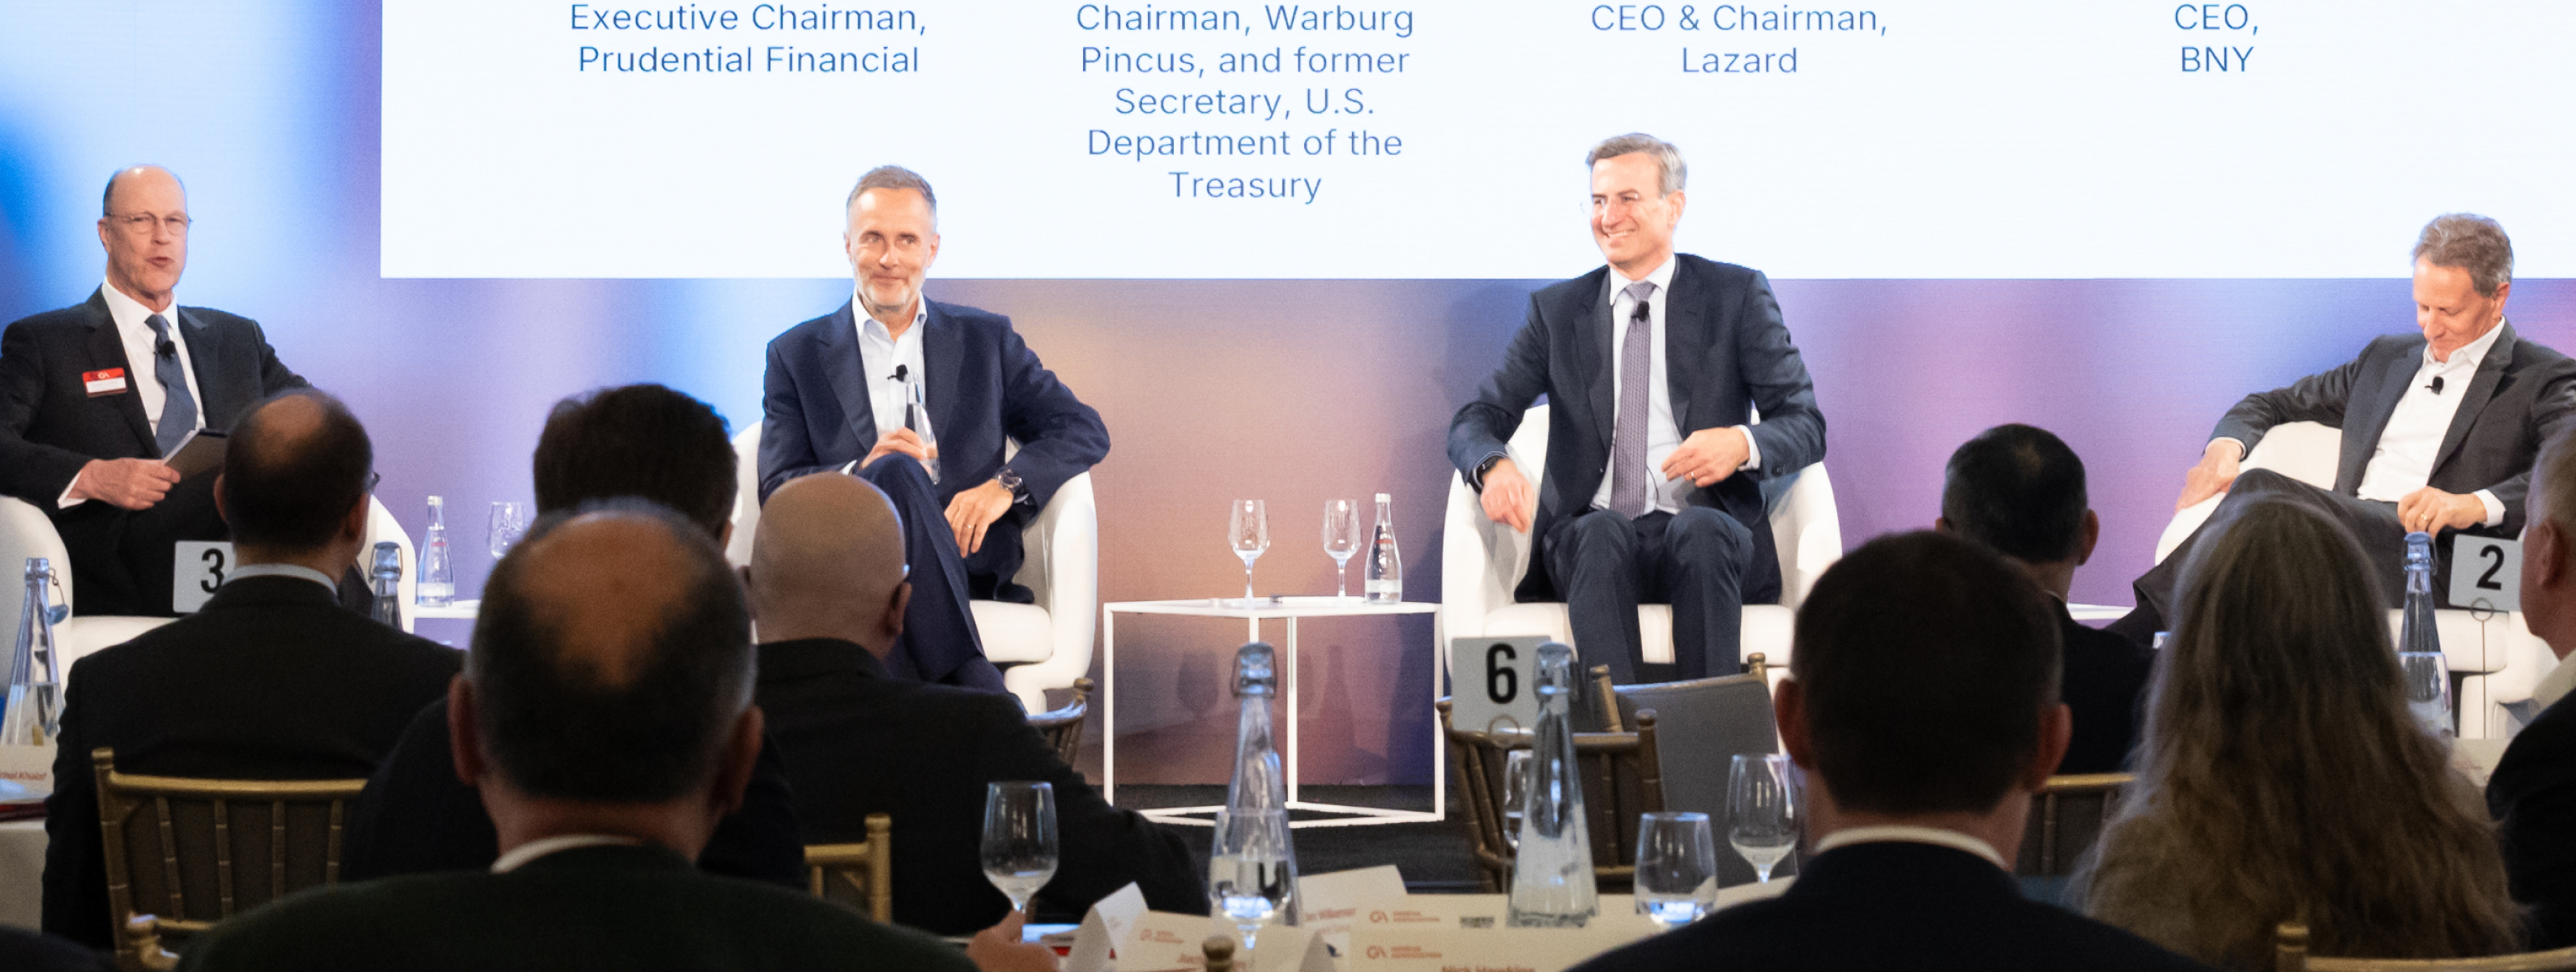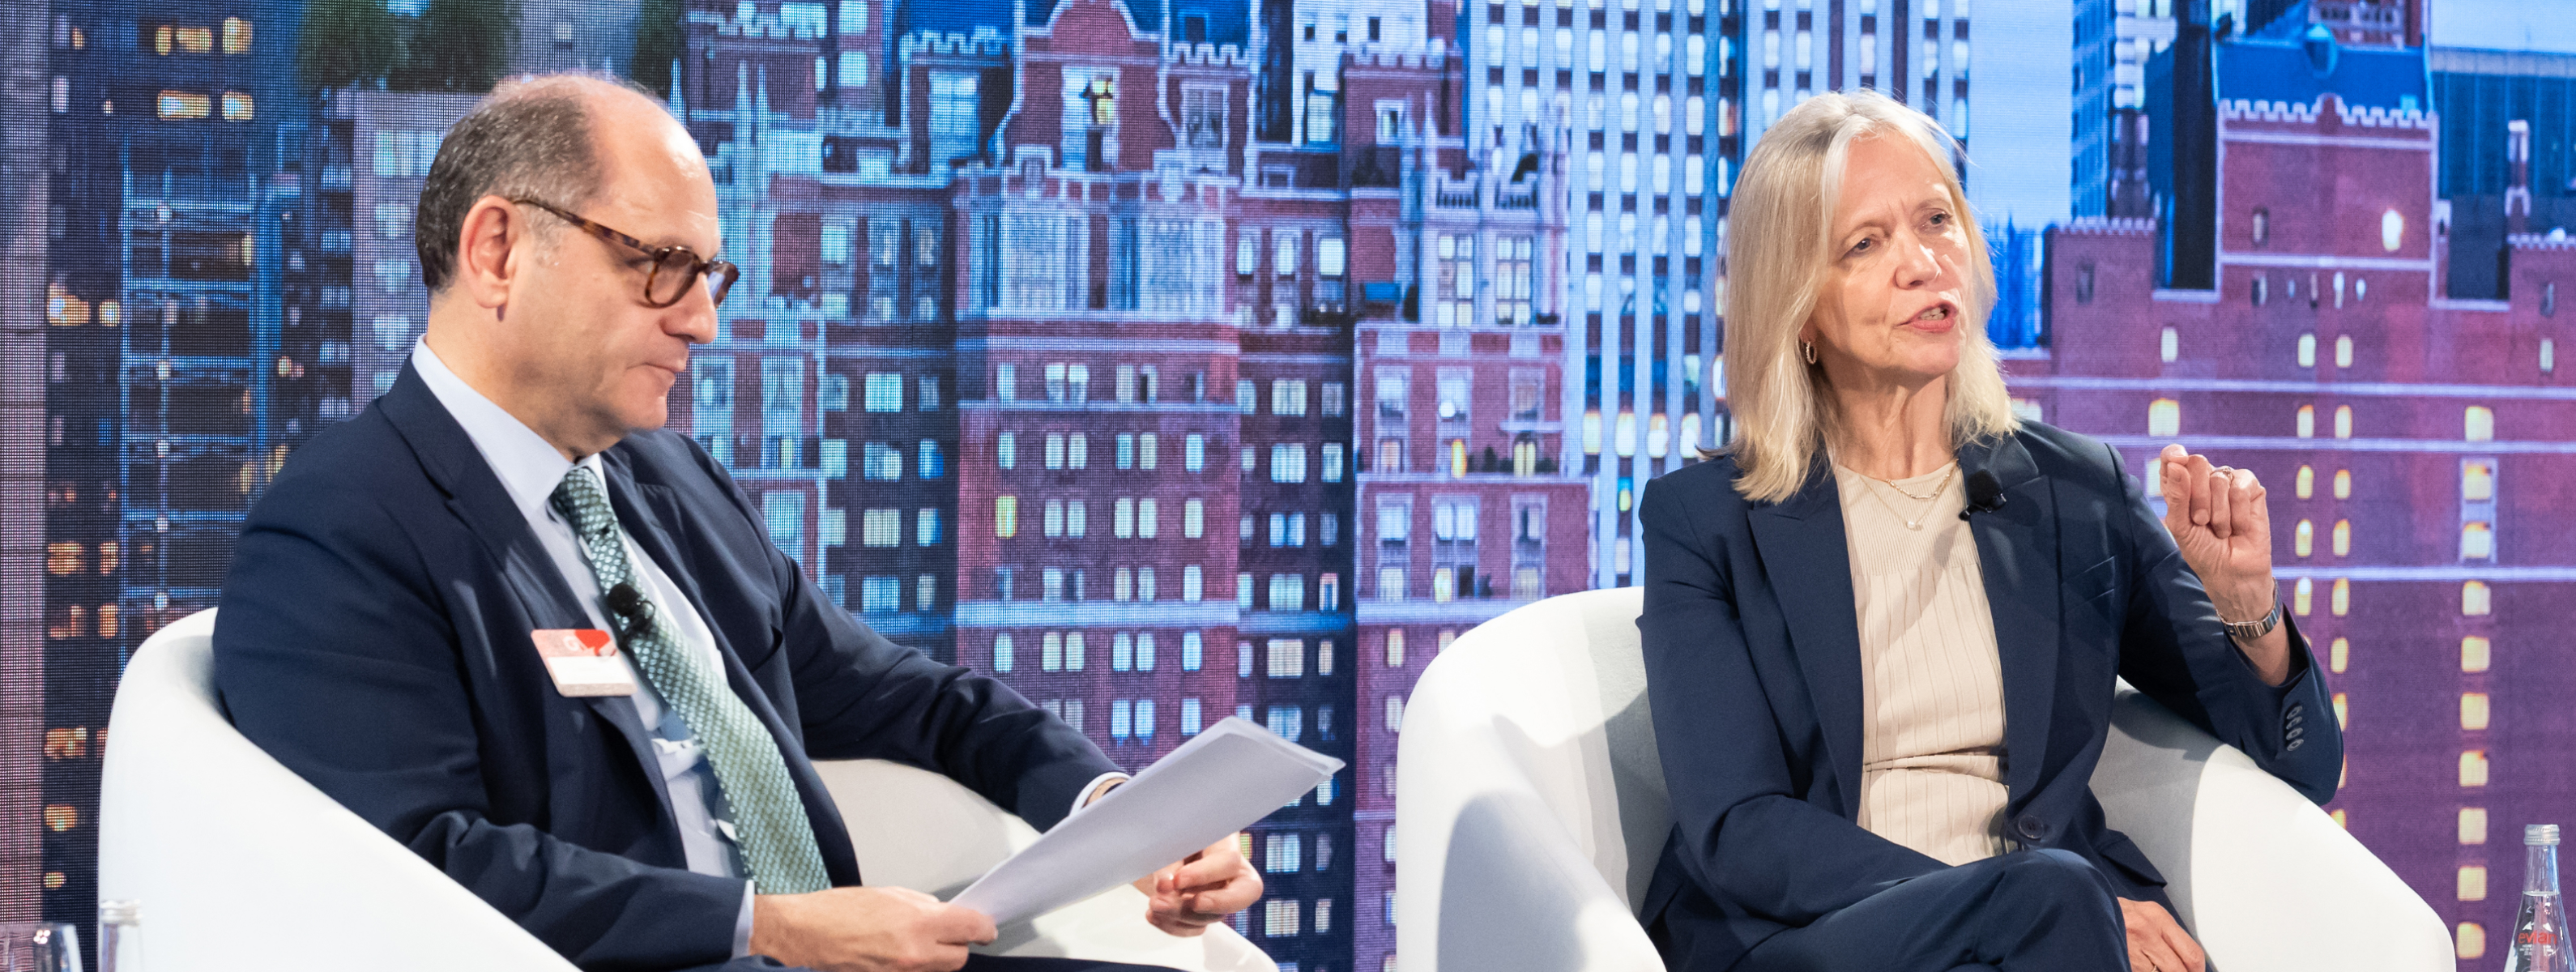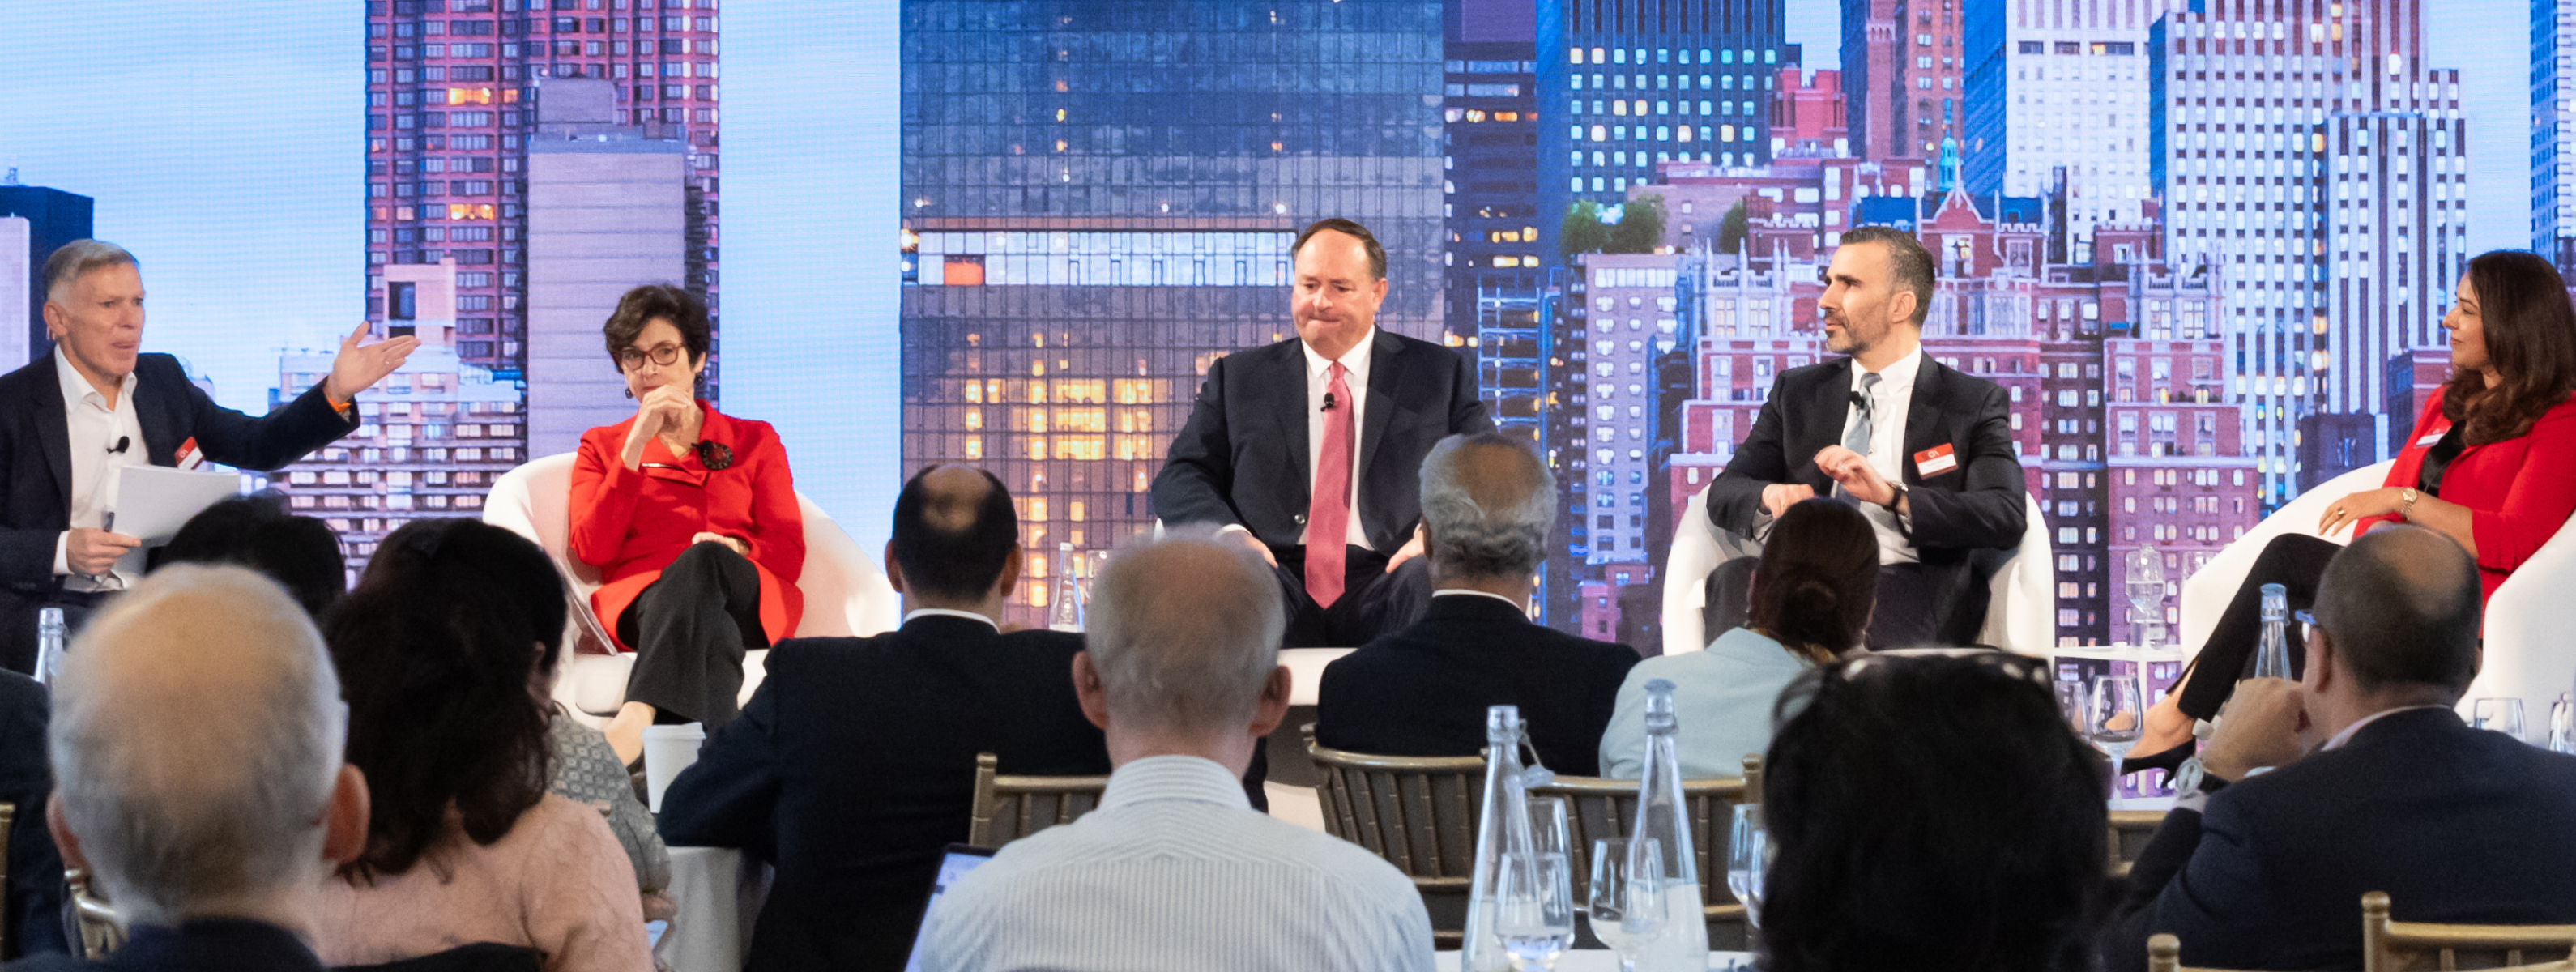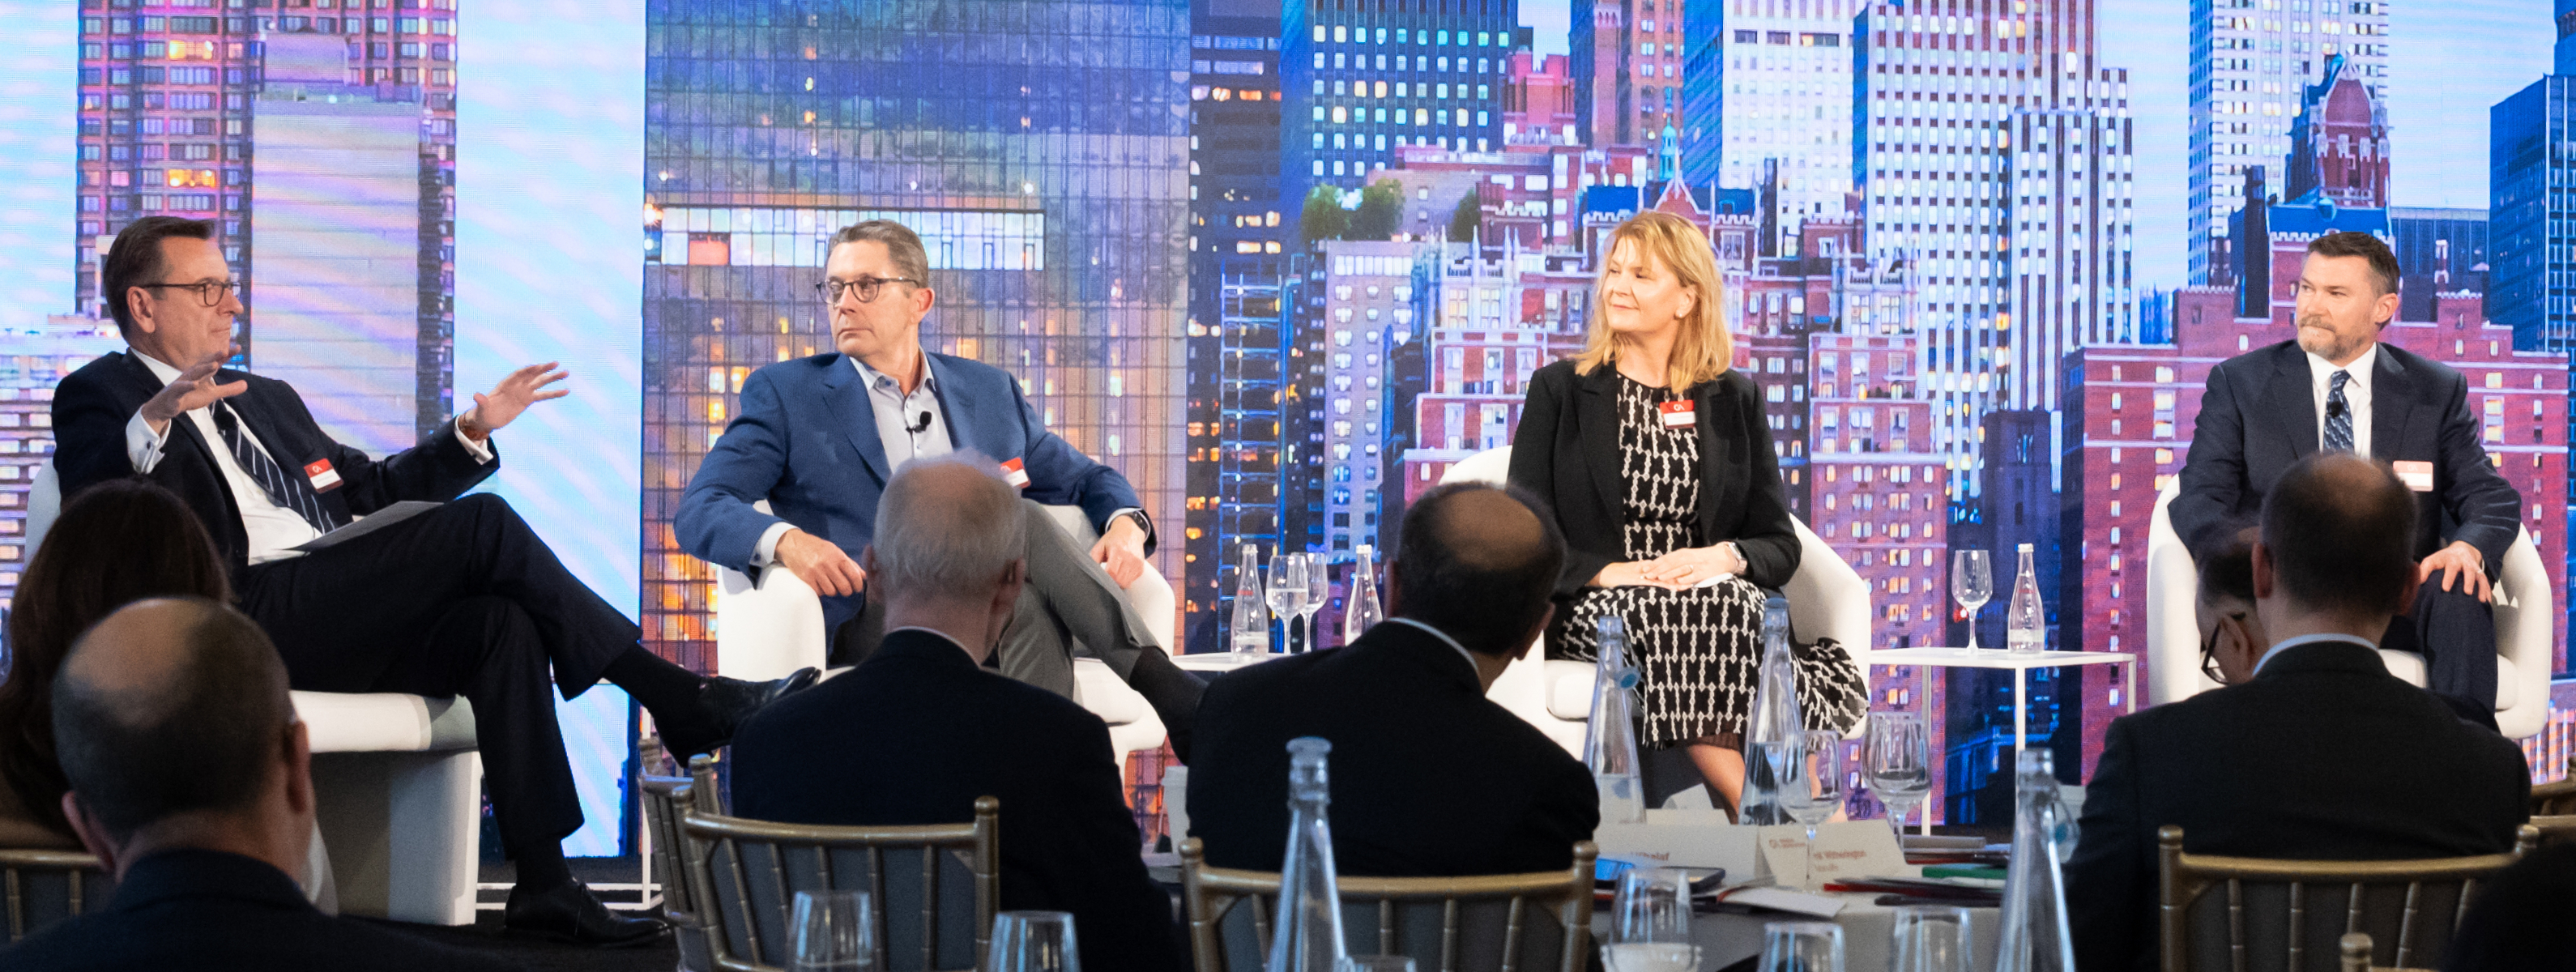
Joachim Wenning, Chairman of the Board of Management, Munich Re; Tim Sweeney, President, CEO & Chairman, Liberty Mutual Insurance; Tina Mitchell, Natural Hazards Commission, New Zealand; Dave Burt, DeltaTerra Capital
The financial impacts of natural disasters are growing, and insurance protection gaps are widening, leaving households, businesses and governments increasingly exposed to the financial and social shocks of climate disasters. As a stark illustration, in 2024, global natural catastrophe losses exceeded USD 300 billion, a 20% increase over the past decade’s average, with a large portion uninsured.
New Zealand’s Natural Hazards Commission provides universal, government-backed coverage for major perils such as earthquakes and tsunamis. Its model has enabled high insurance penetration (95%), streamlined disaster recovery, and supported large-scale managed retreat programs. By integrating scientific research and open data tools, the scheme also enhances public risk awareness and influences land-use decisions.
The US domestic market, on the other hand, faces structural challenges. Rising premiums (up 85% over five years) have outpaced income growth, pricing out many homeowners. Regulatory fragmentation, particularly state-level rate control, hinders risk-based pricing and discourages insurer participation in high-risk areas. California’s regulatory constraints, for example, contrast with Oklahoma’s more flexible, incentive-based approach, which promotes fortification through grants and insurance discounts.
Flood insurance is a major gap in the US. The outdated National Flood Insurance Program provides limited coverage, is often not mandatory, and excludes many high-risk areas. This leaves a large share of flood-exposed homes uninsured.
Improved incentives, risk signalling, and cross-sector collaboration are needed. Many resilience-enhancing investments are financially rational over time but poorly understood by homeowners. Stronger integration between insurers, lenders, regulators, and communities is essential to drive risk reduction and adaptation.