C-Suite


On 24 March, the 2021 edition of The Geneva Association Economic Forum (GAEF) was held virtually. It gathered more than 30 chief economists, chief strategy officers and other senior executives from the global insurance industry – a record turnout. The meeting agenda featured two topics: the global inflation outlook and the role of insurance in promoting the social dimension of ESG.
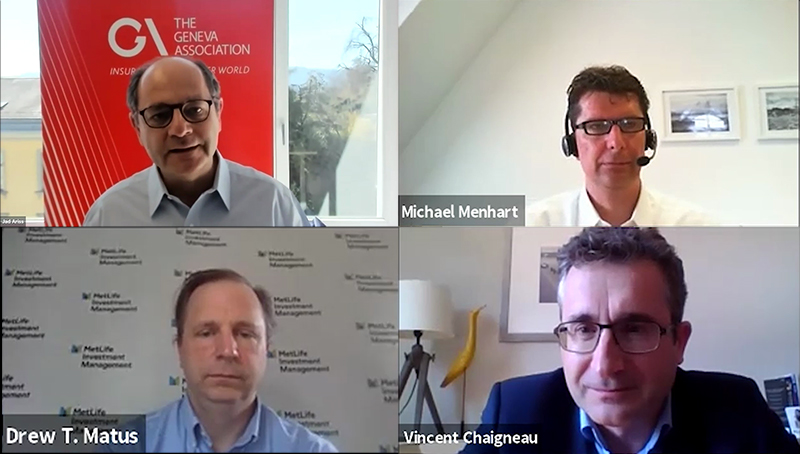
(Top) Jad Ariss, Managing Director, The Geneva Association, Michael Menhart, Chief Economist, Munich Re (Bottom) Drew T. Matus, Chief Market Specialist, Insurance Asset Management, MetLife, Vincent Chaigneau, Head of Research, Generali Insurance Asset Management.
To set the stage, the discussion first explored the history of inflation in the U.S. It surged to double-digit levels in the 1970s, driven by the two ‘oil shocks’ and subsequent drops in manufacturing activity. The COVID-19-induced recession, on the other hand, led to a sharp decline in spending on services rather than manufactured goods. This fundamental difference introduces major uncertainty as to the inflation outlook. Pent-up demand is set to push up inflation in the short term. The medium-term impact, however, will be driven by inflation expectations which, historically, are primarily determined by food and energy prices (which are currently on the rise). On the other hand, the pandemic has accelerated digitalisation which could result in a productivity boom, potentially curbing inflation pressures.
Indeed, the medium-term inflation outlook is associated with significant uncertainty, also in light of a new policy mix, with simultaneously expansionary fiscal and monetary policies. In addition to ‘flooding’ economies with cheap money, some central banks, and the Federal Reserve in particular, have become more tolerant of (temporarily) higher inflation rates. Also, deglobalisation could add to inflation by driving up the cost of consumer goods and inputs. Finally, should inflation ‘show its ugly face’, central banks are unlikely to hike interest rates fast, given the enormous amount of debt in the public and private sector.
During the roundtable discussion a number of additional factors were discussed which all further add to inflation uncertainty. On the one hand, rental inflation (in urban areas) is declining given the dramatic shift in where people desire to live. Also, remote working will dramatically expand the pool of workers, reducing inflationary pressures. On the other hand, global ageing could fuel inflation as ageing people tend to save less and spend more. Further, the labour force could shrink, pushing up wage inflation.
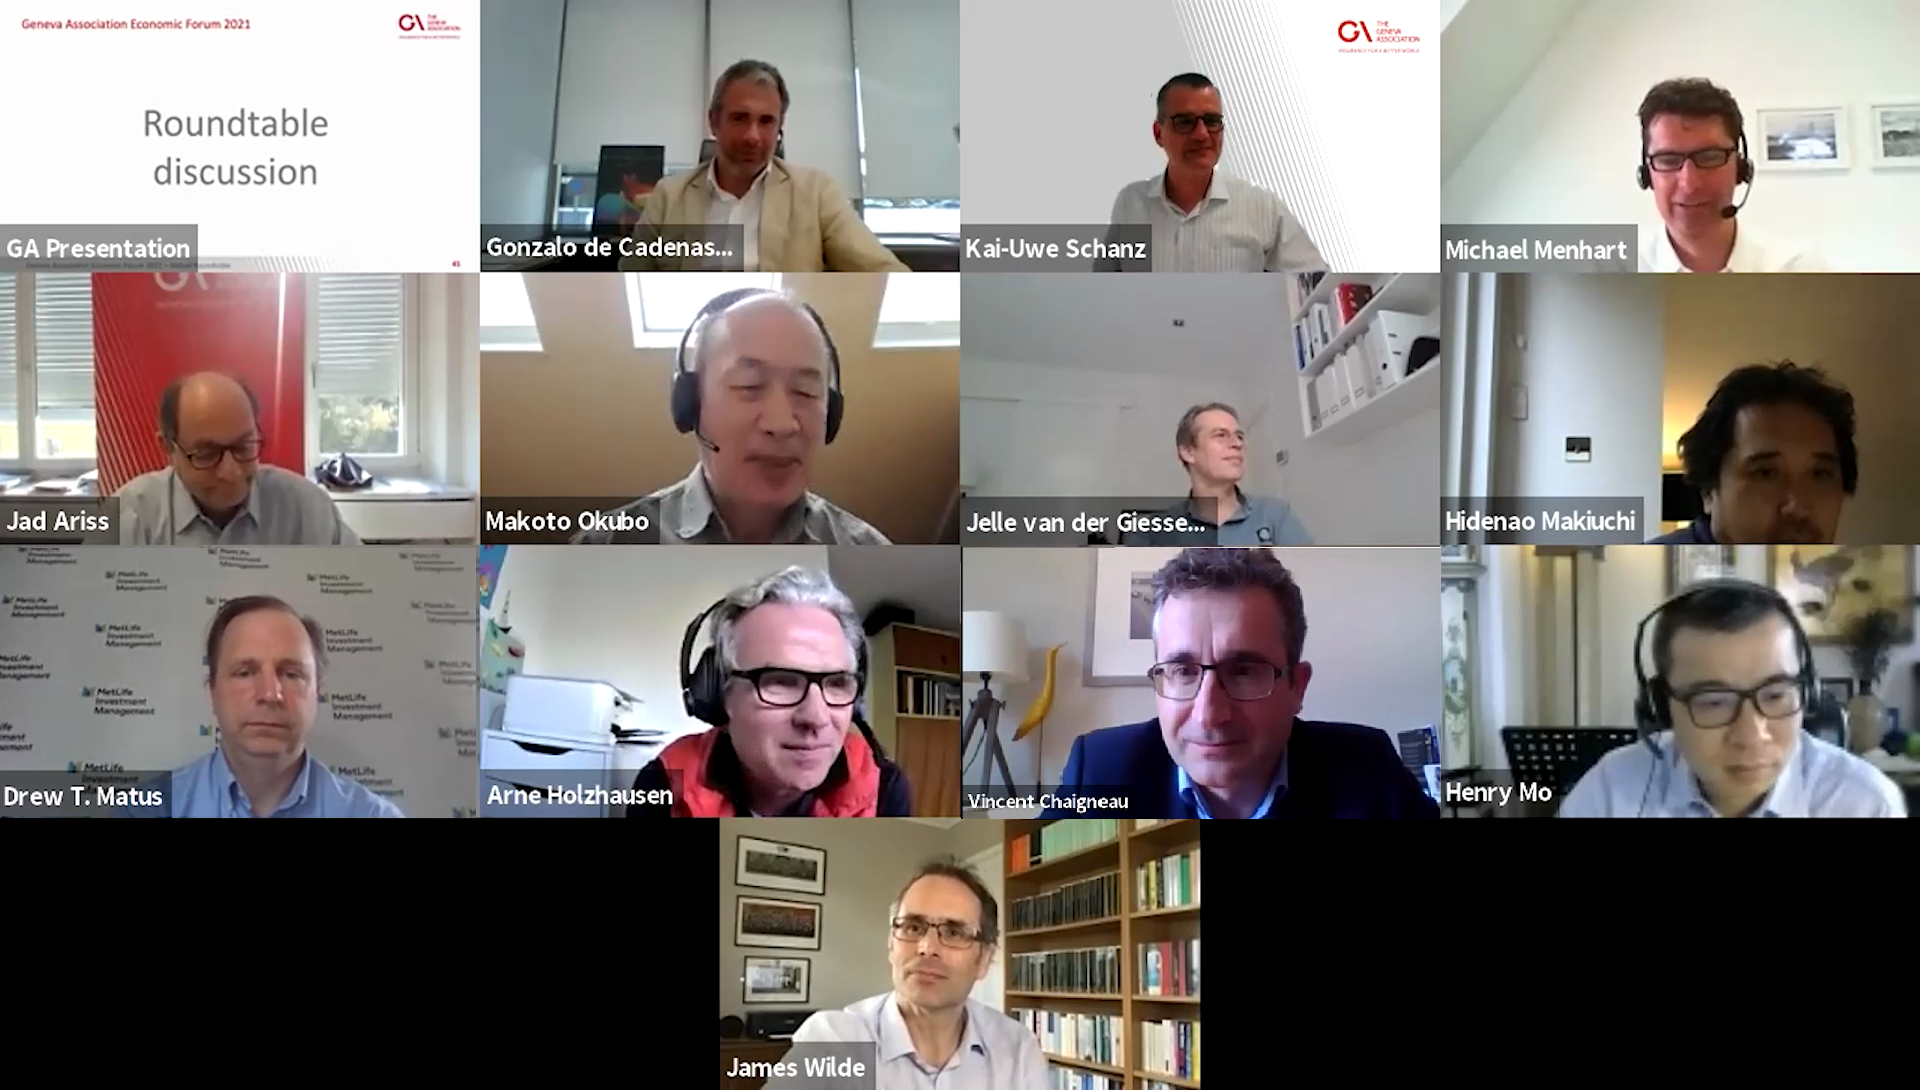
Roundtable discussion at the GAEF 2021
The social dimension of ESG has risen on the agenda of financial services companies as a result of the pandemic and much-amplified societal imbalances as well as in response to heightened legislative and regulatory activity. Stakeholder expectations – vis-à-vis companies’ impact on human rights, gender and race diversity and social inequality – are mounting, catalysing legal and regulatory developments such as the German Due Diligence Act and the EU’s social taxonomy project. But ESG is not only about managing reputational risks and compliance. It is also about creating positive social impact through the core business of insurance, e.g. via microinsurance or by incentivising more responsible individual behaviours. However, there are major open questions remaining. For example, who sets the standards for societal objectives (which is trickier than for climate or environmental objectives)? And how do we measure progress in achieving those objectives?
Participants highlighted that ESG objectives align with the fundamental business model of insurance which is about risk-sharing and mitigation. Therefore, the most obvious way for insurers to contribute to ESG objectives is to build on their tested business model. Additional efforts should be predicated on transparency, e.g. by disclosing ESG-related risks and building a taxonomy to help guide investment and underwriting decisions.
During the debate, it was mentioned that insurers need to be cautious in referring to commonly agreed standards for risk of being perceived as imposing ‘Western’ views on the rest of the world. At the same time, insurers face pressure from their stakeholders to define a clear position on corporate social ESG objectives, irrespective of and going beyond guidance from politicians or multilateral organisations. Such objectives might have to be more ambitious than simply pursuing existing insurance business models in order to sustainably defend the industry’s ‘license to operate’.