C-Suite
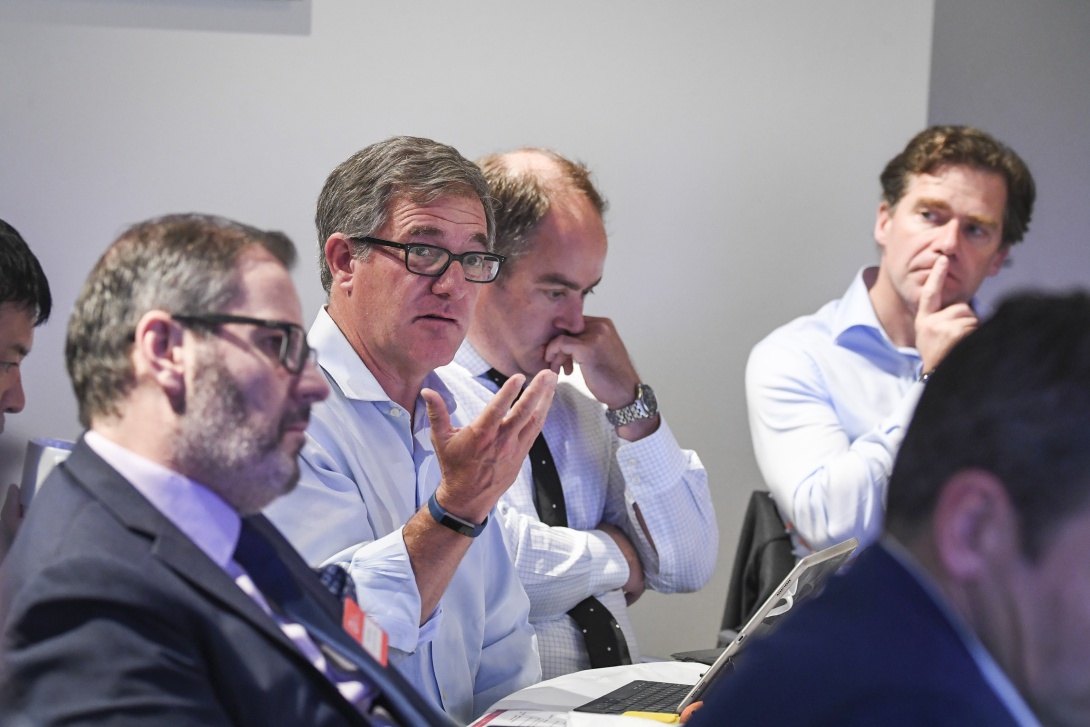


The Geneva Association's 13th Conference of Chief Investment Officers, generously hosted by LocalTapiola Group, will be held 5-6 September 2019 in Helsinki, Finland.
This annual Conference enables insurance CIOs and experts to exchange experiences on key issues facing insurance asset management and aims to strengthen the insurance industry’s dialogue with external stakeholders.
Insurers have many worries in the present environment. Some are perennial concerns, such as finding reliable sources of yield, ensuring capital efficiency and managing shareholders and regulators. Other concerns are newer, such as heightened macroeconomic uncertainty and emerging risks, notably climate change.
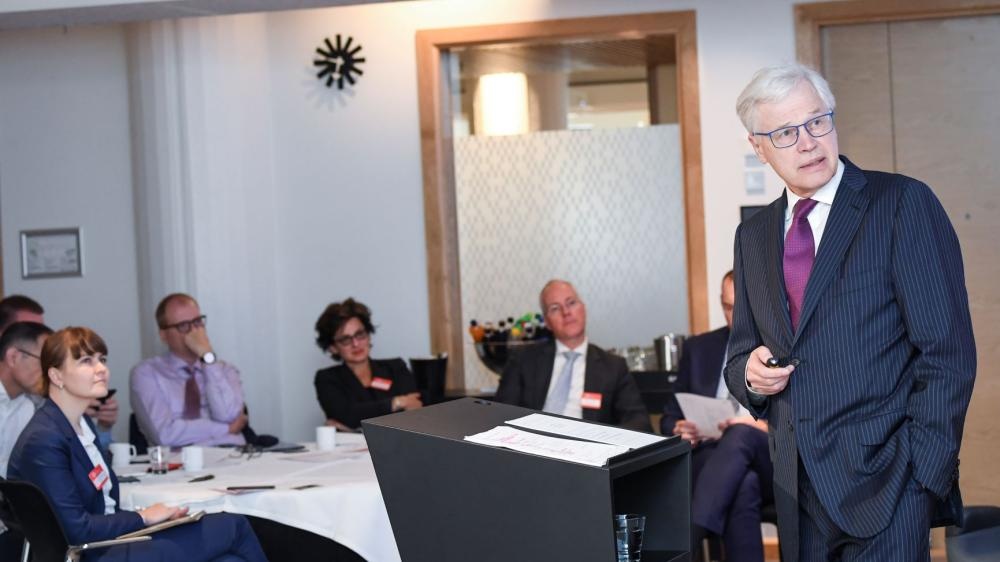
Professor Bengt Holmström, 2016 Nobel Laureate in Economics, provided insights on key issues in the markets. He argued that debt was information insensitive, particularly when underpinned with safe collateral, and that its opacity is beneficial to its liquidity and resilience. This is not to say that risk in not hiding in the tail, but the reliance of debt on coarse—and often mechanical —ratings obviates the need for deeper price discovery and reduces the volatility that comes with greater transparency.
This is why, in a crisis, a ‘bad bank’ solution makes sense. It effectively reduces transparency and allows the debt time to be worked out. Professor Holmström cautioned that greater transparency – a key push today – implies less liquidity.
Today there is a global shortage of safe assets or collateral. This is attributable to damage from the last financial crisis, hoarding of reserve assets (largely US dollar assets) by many parties, demographics, the growth of intangible assets in the form of new technologies, and large amounts of share buybacks. According to Professor Holmström, resolving this is a prerequisite to fixing the conundrum of low-interest rates, low inflation, low unemployment and low investment. Central banks have a role to play given the size of their balance sheets, but it is also important to explore other avenues, such as harnessing fiscal policy for more infrastructure investments, introducing new safe assets such as the IMF’s SDRs and finding new private substitutes.
Insurers’ challenges support Professor Holmström’s assessment. A crash may not be imminent, but there was general agreement that low-interest rates and the challenges associated with them would continue. With 30% of bonds yielding negative returns, negative interest rates in the U.S. in the future may not sound so far-fetched.
Participants largely agreed that escalating trade tensions would lead to slowdowns and recessions, declining inflation expectations and a further drop in bond yields. In this environment, the consensus was that while monetary policy was loosening, the unconventional methods that worked in 2008 would lose their effectiveness. Fiscal expansion is the next possible frontier, which may also help meet the demand for safe longer-dated assets.
The proposed solutions, however – namely, more monetary and possible easing – have an often unappreciated and significant impact on the two key pillars of the savings landscape: the insurance industry and pensions, which have seen liabilities rise and returns fall inexorably. These segments are critical to sustaining corporate and sovereign bond markets, a key part of the global financial infrastructure. Policymakers, however, are more focused on banks, businesses and consumers. This environment is corrosive to the insurance business model and to global savings, and over time, it will be detrimental to global investment and financial stability as well.

Longer-term, other key risks need to be managed, notably climate change and other Environmental, Social and Governance (ESG) concerns. Much attention has already been devoted to these new dimensions, but the CIOs in attendance were on this occasion focused on how to integrate them into their portfolios, as well as the role of regulators and policymakers.
Twenty percent of the insurance companies that The Geneva Association’s members represent see climate change as a strategic issue with implications for both sides of the balance sheet. For the remaining GA member companies, their focus thus far has been on sustainability and corporate social responsibility.
Participants expressed challenges in implementation. A holistic approach that links both sides of the balance sheet is a stiff undertaking, particularly when historical data on climate change does not offer much insight, and anticipated outcomes – though uniform in qualitative assessment – lack precision.
The infrastructure needed to effect change is slow in coming. The required common standards and data sources are lagging. Work is happening – the Bank of England’s recent climate risk scenarios aimed at insurers are a good example of attempts toward a common framework – but the industry still needs collaboration and buy-in at the top level.
There are opportunities for those willing to put in the effort. Addressing climate change does not mean reducing returns but rather opening up new investment avenues. Infrastructure is an area of fast-growing interest, given the long duration, significant scale and confluence with the interests of governments around the world. Here, the role of policymakers in supporting and de-risking long-term investments is critical, through mechanisms such as regulatory reform and growth-friendly policies.