

The New Insurability Frontier: Policy and Regulation for Today’s Global Risks
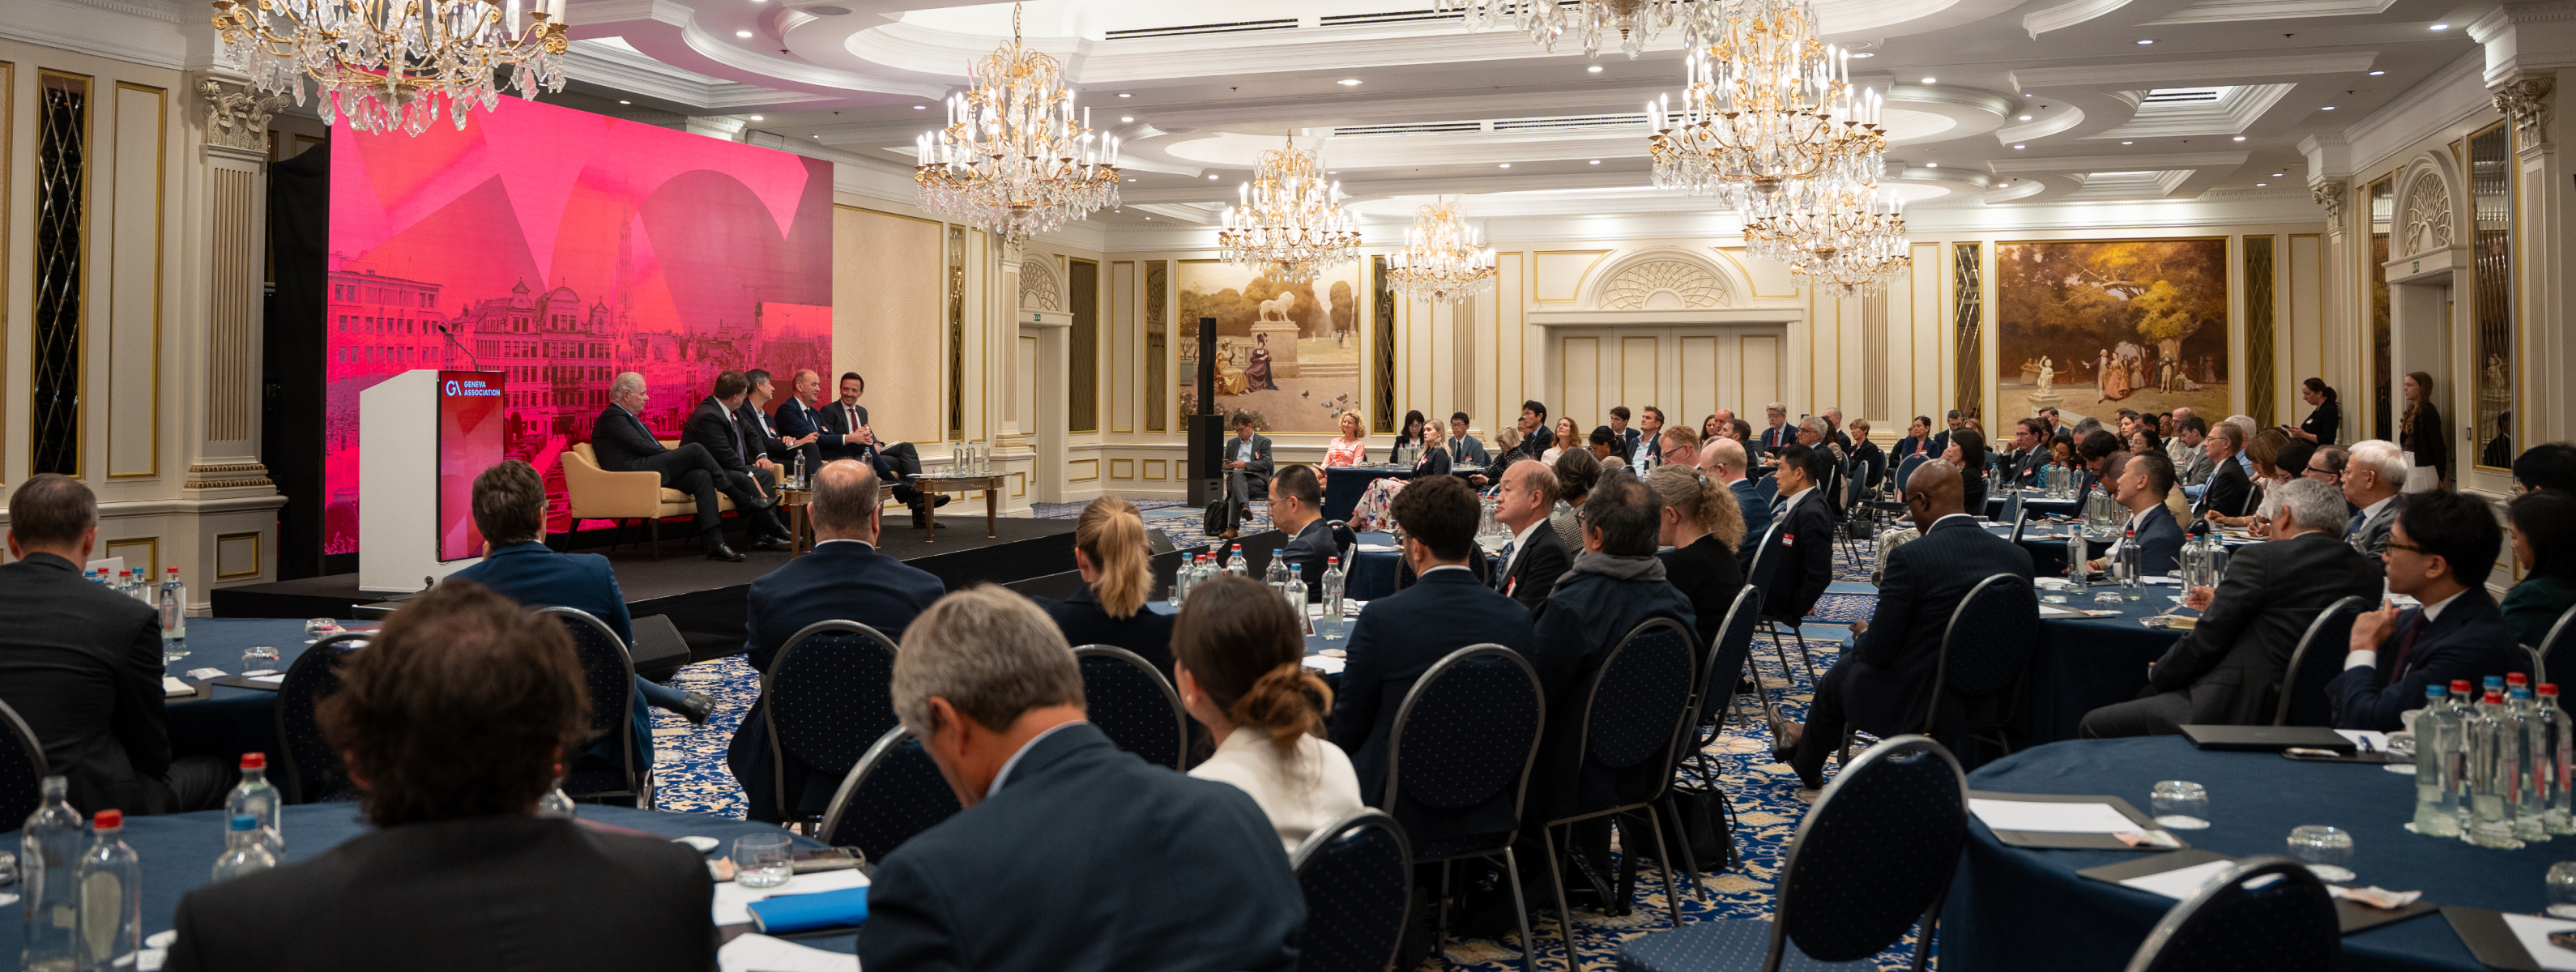
Against a backdrop of geopolitical tension, rapid technological change and growing pressure on public- and private-protection systems, the Geneva Association’s 2026 Programme on Regulation and Supervision examined how policy, regulation and supervision can help insurance continue to fulfill its role in society. Across the discussions, a consistent message emerged: insurance companies and the frameworks they operate within need to adapt to new risks, and enable innovation.
At the heart of this is the question of insurability. As risks evolve and become more interconnected, the challenge is not simply to regulate them, but to create the conditions in which they can continue to be understood, managed and transferred. Policymakers, regulators, supervisors and insurers need to anticipate change and work across traditional sectoral and geographic boundaries.
Navigating a more fragmented world
Geopolitical fragmentation is increasingly affecting the environment in which insurers operate. Shifts in trade relationships, supply chains and economic policy can create inflationary pressures, constrain the international diversification of risk and introduce new dependencies.
Participants emphasised that greater economic security does not necessarily require retreating from international markets. Diversification, open markets and clear rules remain important sources of resilience. At the same time, geopolitical risk is becoming a more explicit business consideration for insurers, requiring firms to understand vulnerabilities across investments, supply chains and counterparties.
These developments also reinforce the importance of international regulatory cooperation. As financial systems become more fragmented, unnecessary divergence between regulatory regimes can itself create friction, while greater consistency can facilitate the effective allocation of capital and risk.
 Petra Hielkema, Chairperson, EIOPA and Vice-Chair, IAIS Executive Committee
 Lard Friese, CEO, Aegon and Chair, Geneva Association; Jad Ariss, Managing Director, Geneva Association
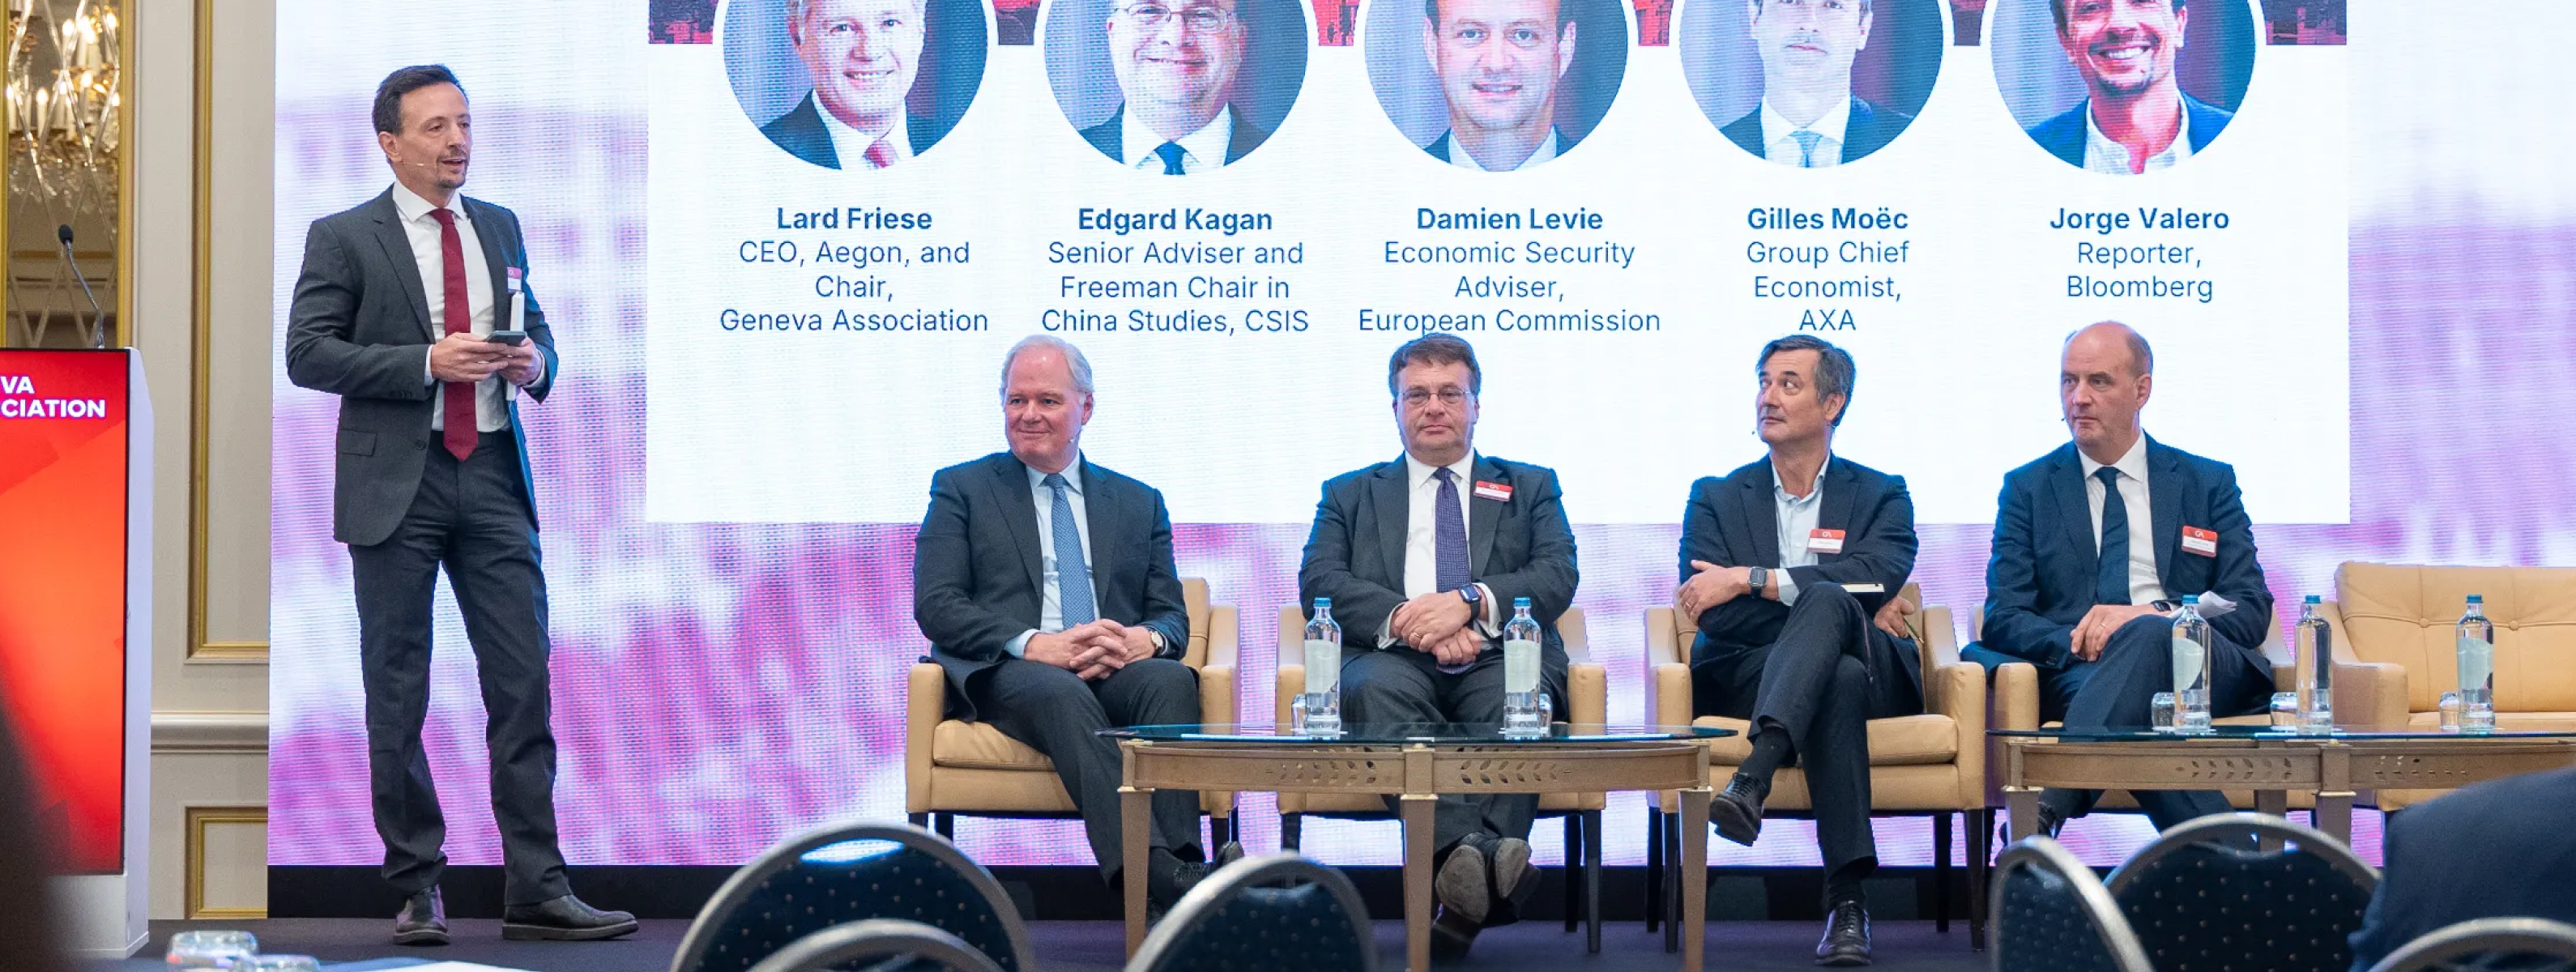 Jorge Valero, Reporter, Bloomberg; Lard Friese, CEO, Aegon and Chair, Geneva Association; Edgard Kagan, Senior Adviser and Freeman Chair in China Studies, CSIS; Gilles Moëc, Group Chief Economist, AXA; Damien Levie, Economic Security Adviser, European Commission
Closing the retirement protection gap
Demographic change is placing increasing responsibility on individuals to prepare financially for longer lives. Discussions on retirement highlighted challenges across the entire journey: encouraging people to save, investing those savings appropriately and ultimately converting accumulated assets into sustainable retirement income.
There is no single policy solution. Automatic enrolment, tax incentives, accessible advice and simpler products can all help overcome inertia, while insurers can contribute by combining long-term investment with protection against uncertainties such as longevity.
The discussion also highlighted that retirement policy needs to go beyond accumulation and address the decumulation phase. Individuals face complex choices about when and how to draw down their savings, without knowing how long they will live or what care needs may arise. There is a role for insurers to play in helping people navigate this transition – through appropriate products, guidance and advice, in order to help reduce the retirement protection gap.
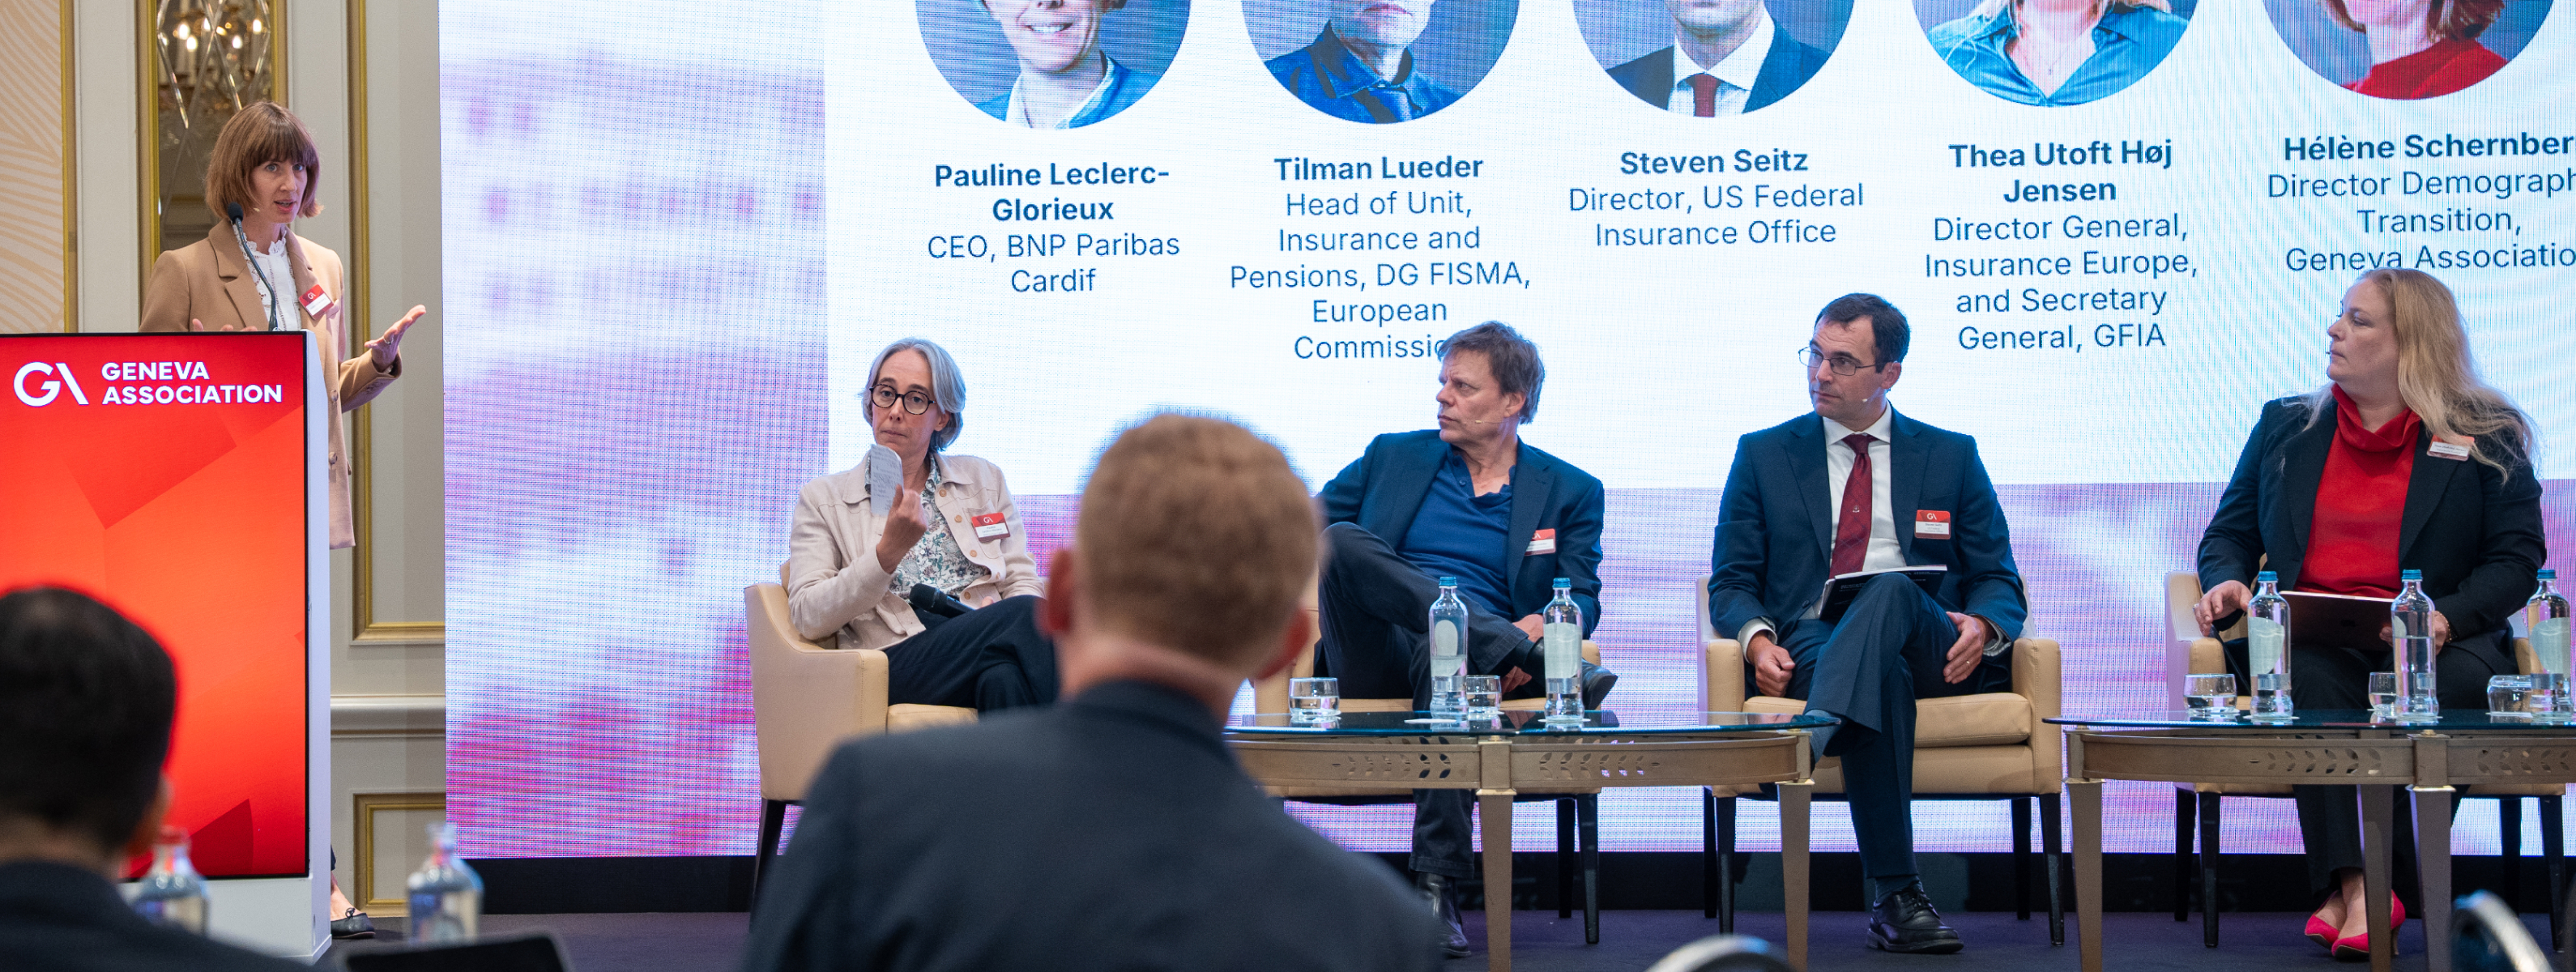 Hélène Schernberg, Director Demographic Transition, Geneva Association; Pauline Leclerc-Glorieux, CEO, BNP Paribas Cardif; Tilman Lueder, Head of Unit, Insurance and Pensions, DG FISMA, European Commission; Steven Seitz, Director, US Federal Insurance Office; Thea Utoft Høj Jensen, Director General, Insurance Europe and Secretary General, GFIA
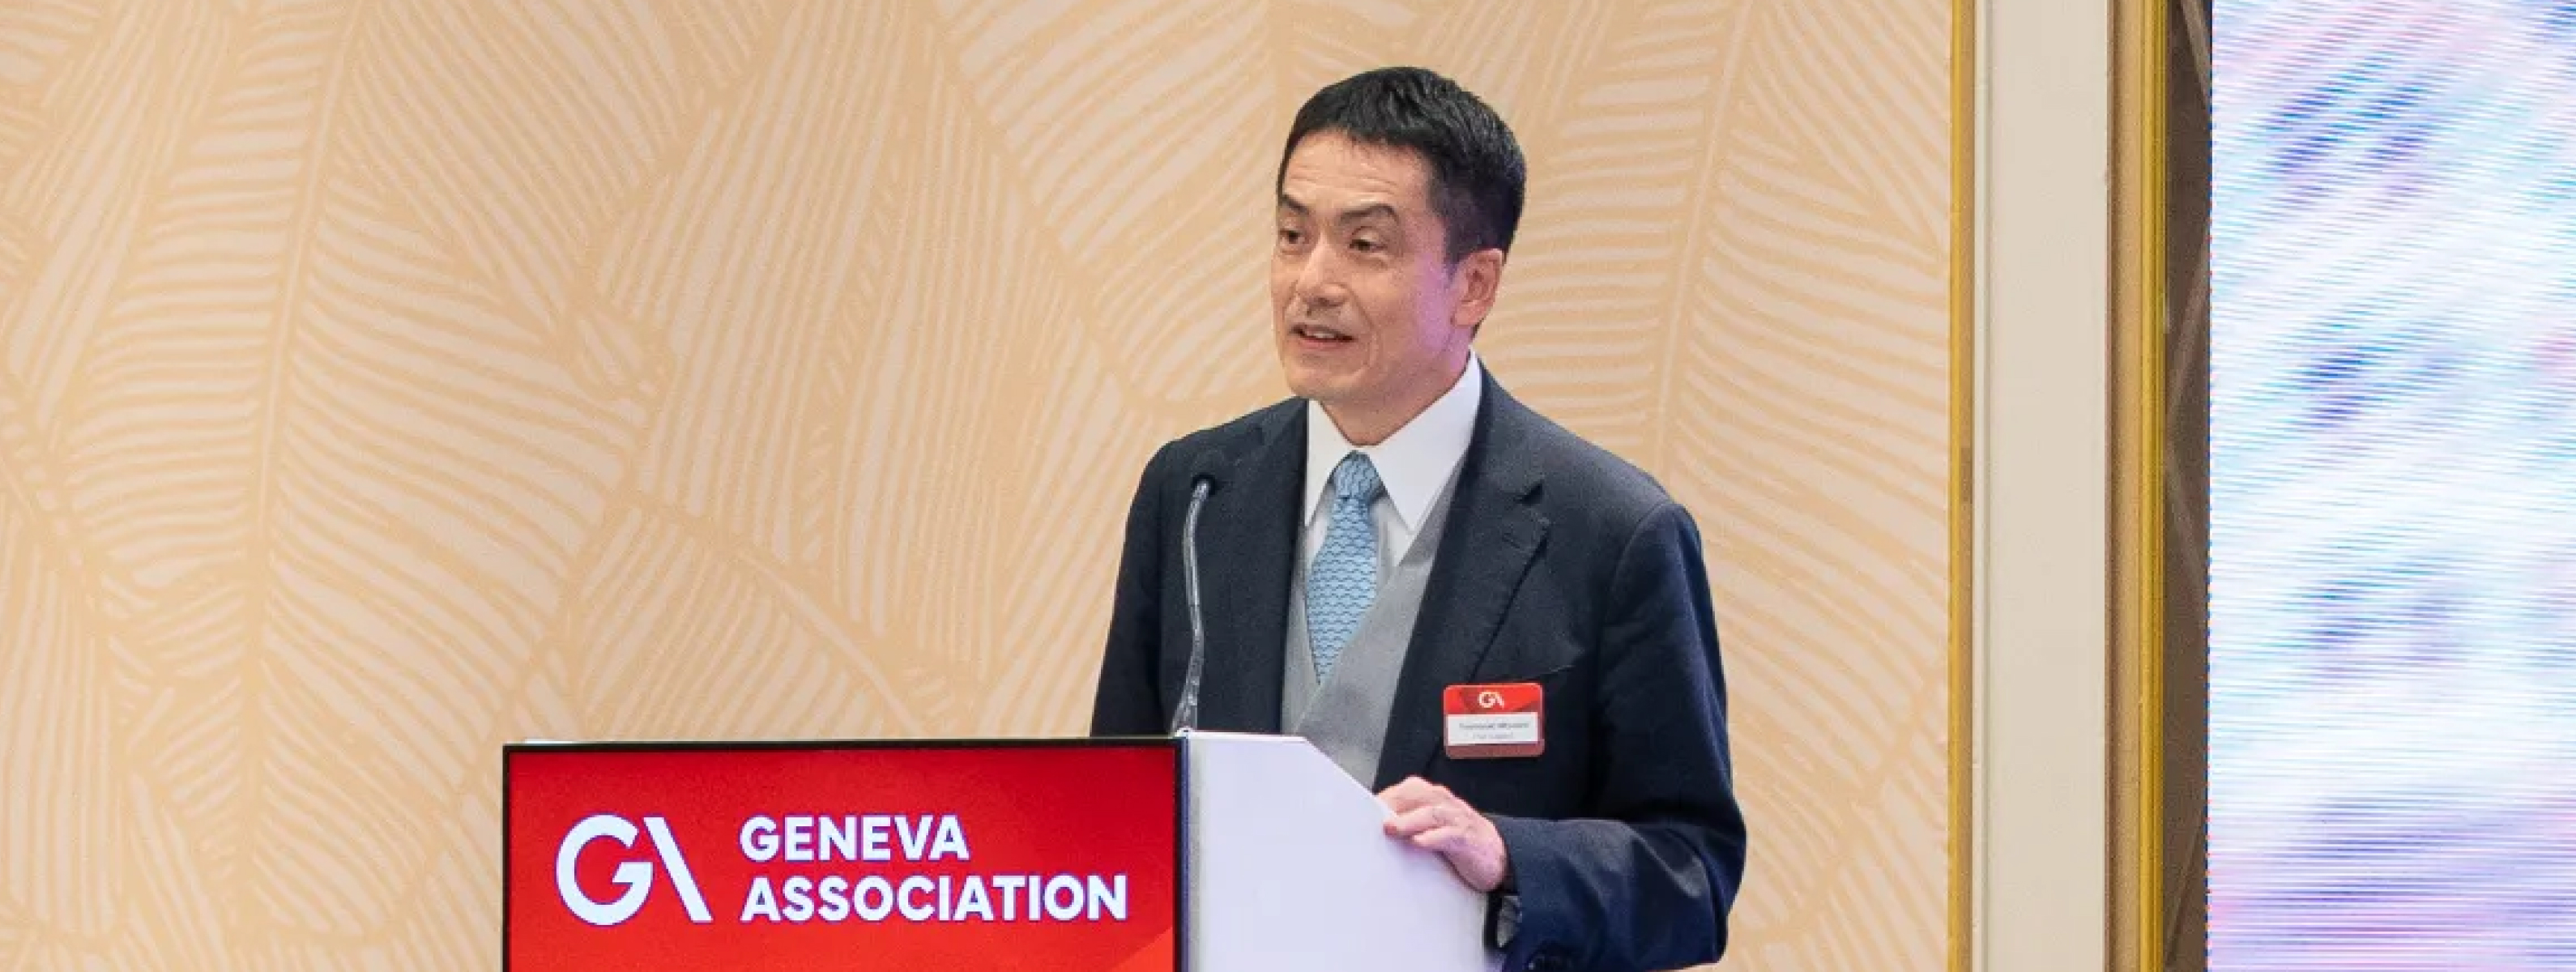 Toshiyuki Miyoshi, Vice Minister for International Affairs, Financial Services Agency of Japan and Chair, IAIS Executive Committee
Enabling the climate transition
The area of industrial decarbonisation is an illustration of how insurance regulation increasingly intersects with policy in other sectors. Scaling technologies such as carbon capture and storage, clean energy and low-carbon industrial processes requires not only significant capital but effective management and allocation of unfamiliar risks.
Insurance can help projects progress from early development towards bankability, investability and scale through risk engineering, underwriting, and investment. The earlier engagement of insurers can be particularly valuable, allowing them to help identify and mitigate risks while projects and technologies are still being designed. For emerging technologies where risks remain difficult for the private market to absorb alone, public-private risk-sharing mechanisms can also help mobilise insurance capacity and investment.
Creating the conditions for this will require stable policy, effective permitting and regulatory frameworks that recognise appropriate forms of credit enhancement and risk mitigation. More broadly, progress will depend on collaboration across insurers, investors, governments and industries.
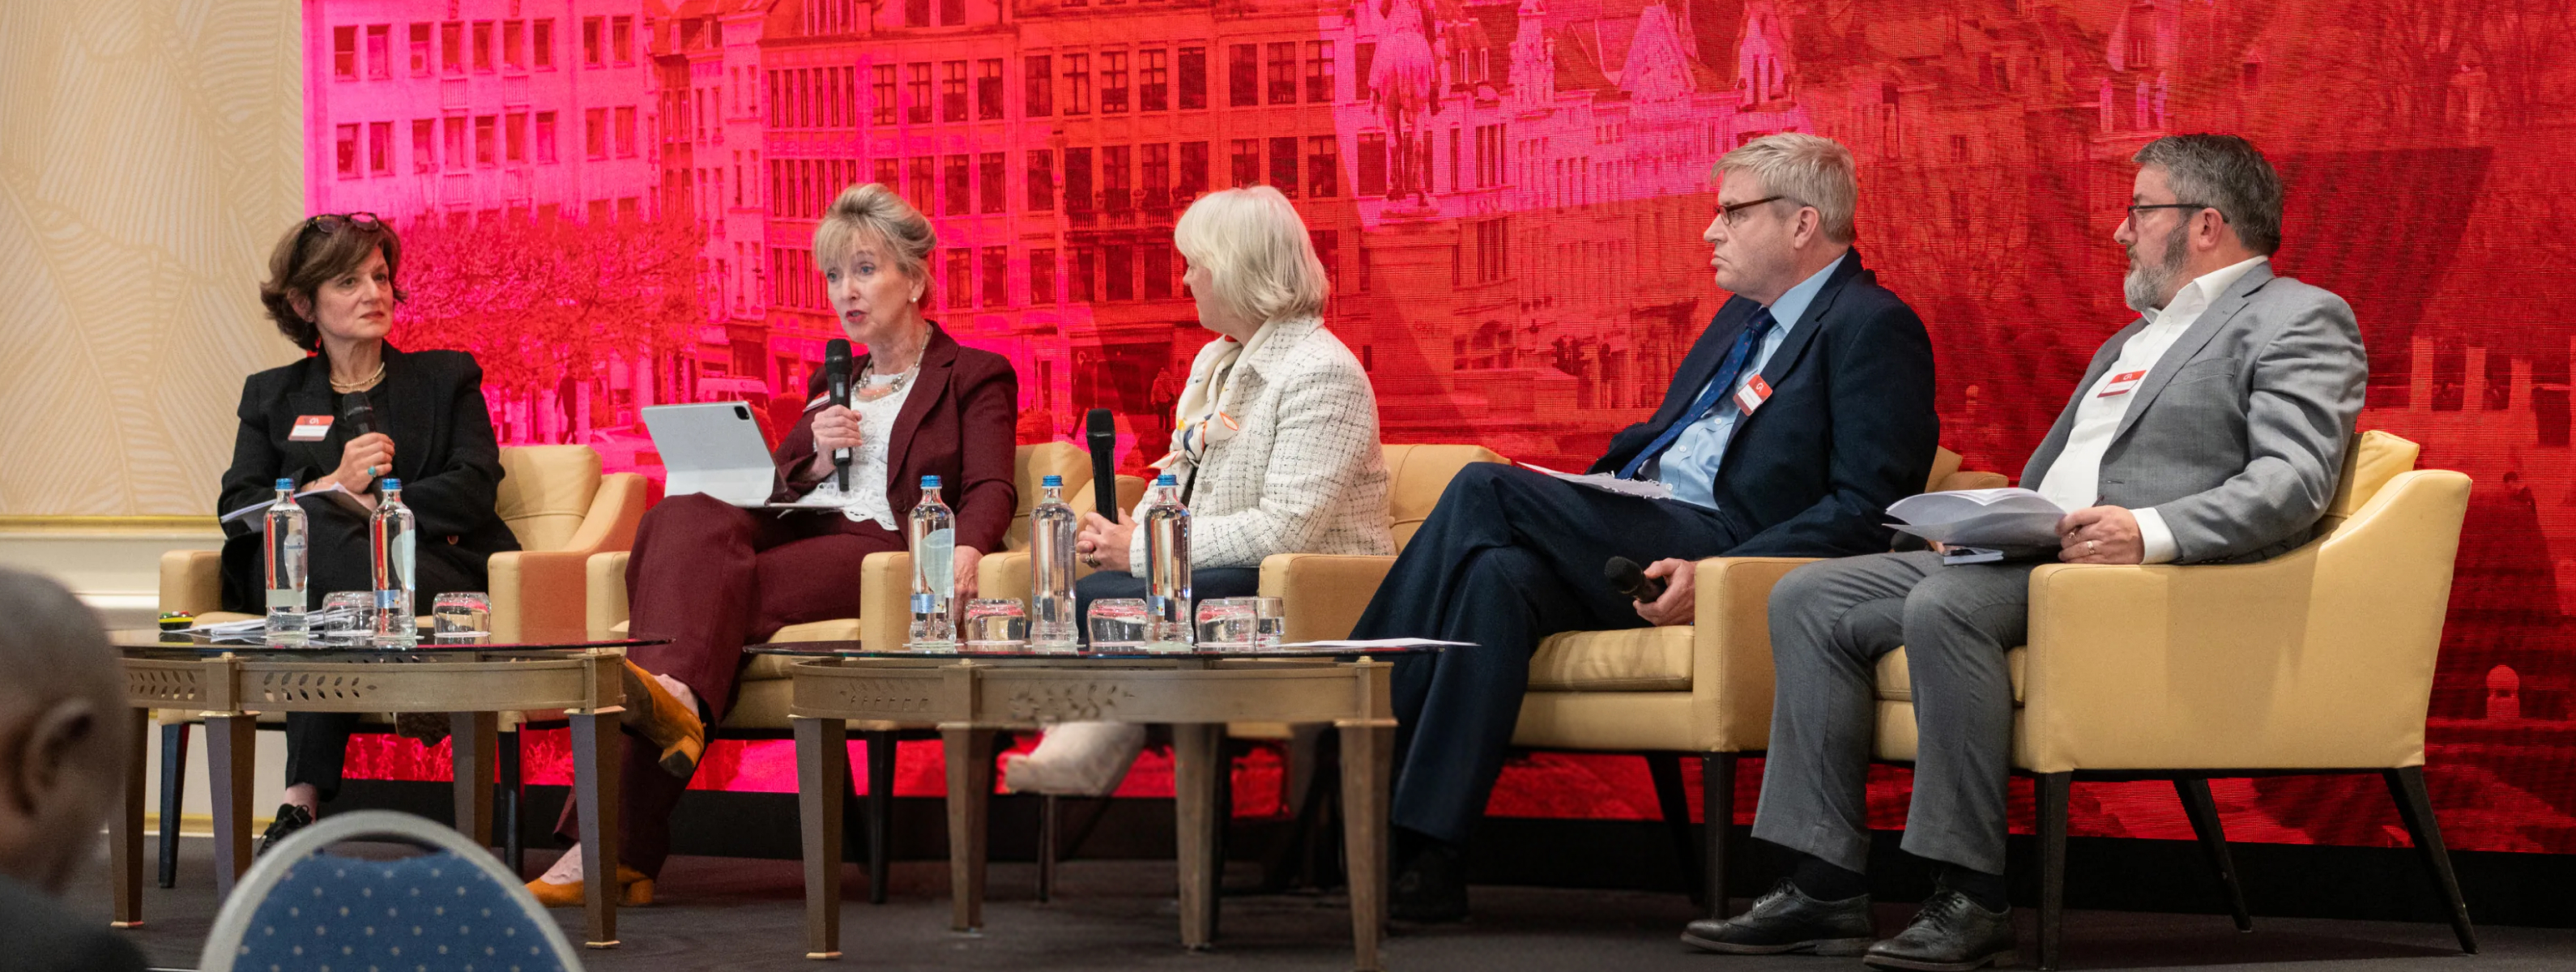 Maryam Golnaraghi, Director Climate Change & Environment, Geneva Association; Sonja Gibbs, Managing Director, Global Markets and Policy, Institute of International Finance; Lesley Harding, Global Head of Strategic Relationships, Energy & Transition, Liberty Mutual; Andrew Purvis, Director, Sustainable Manufacturing, World Steel Association; Iain Macdonald, Principal Advisor Technical Carbon Advocacy, Carbon Strategy, Shell
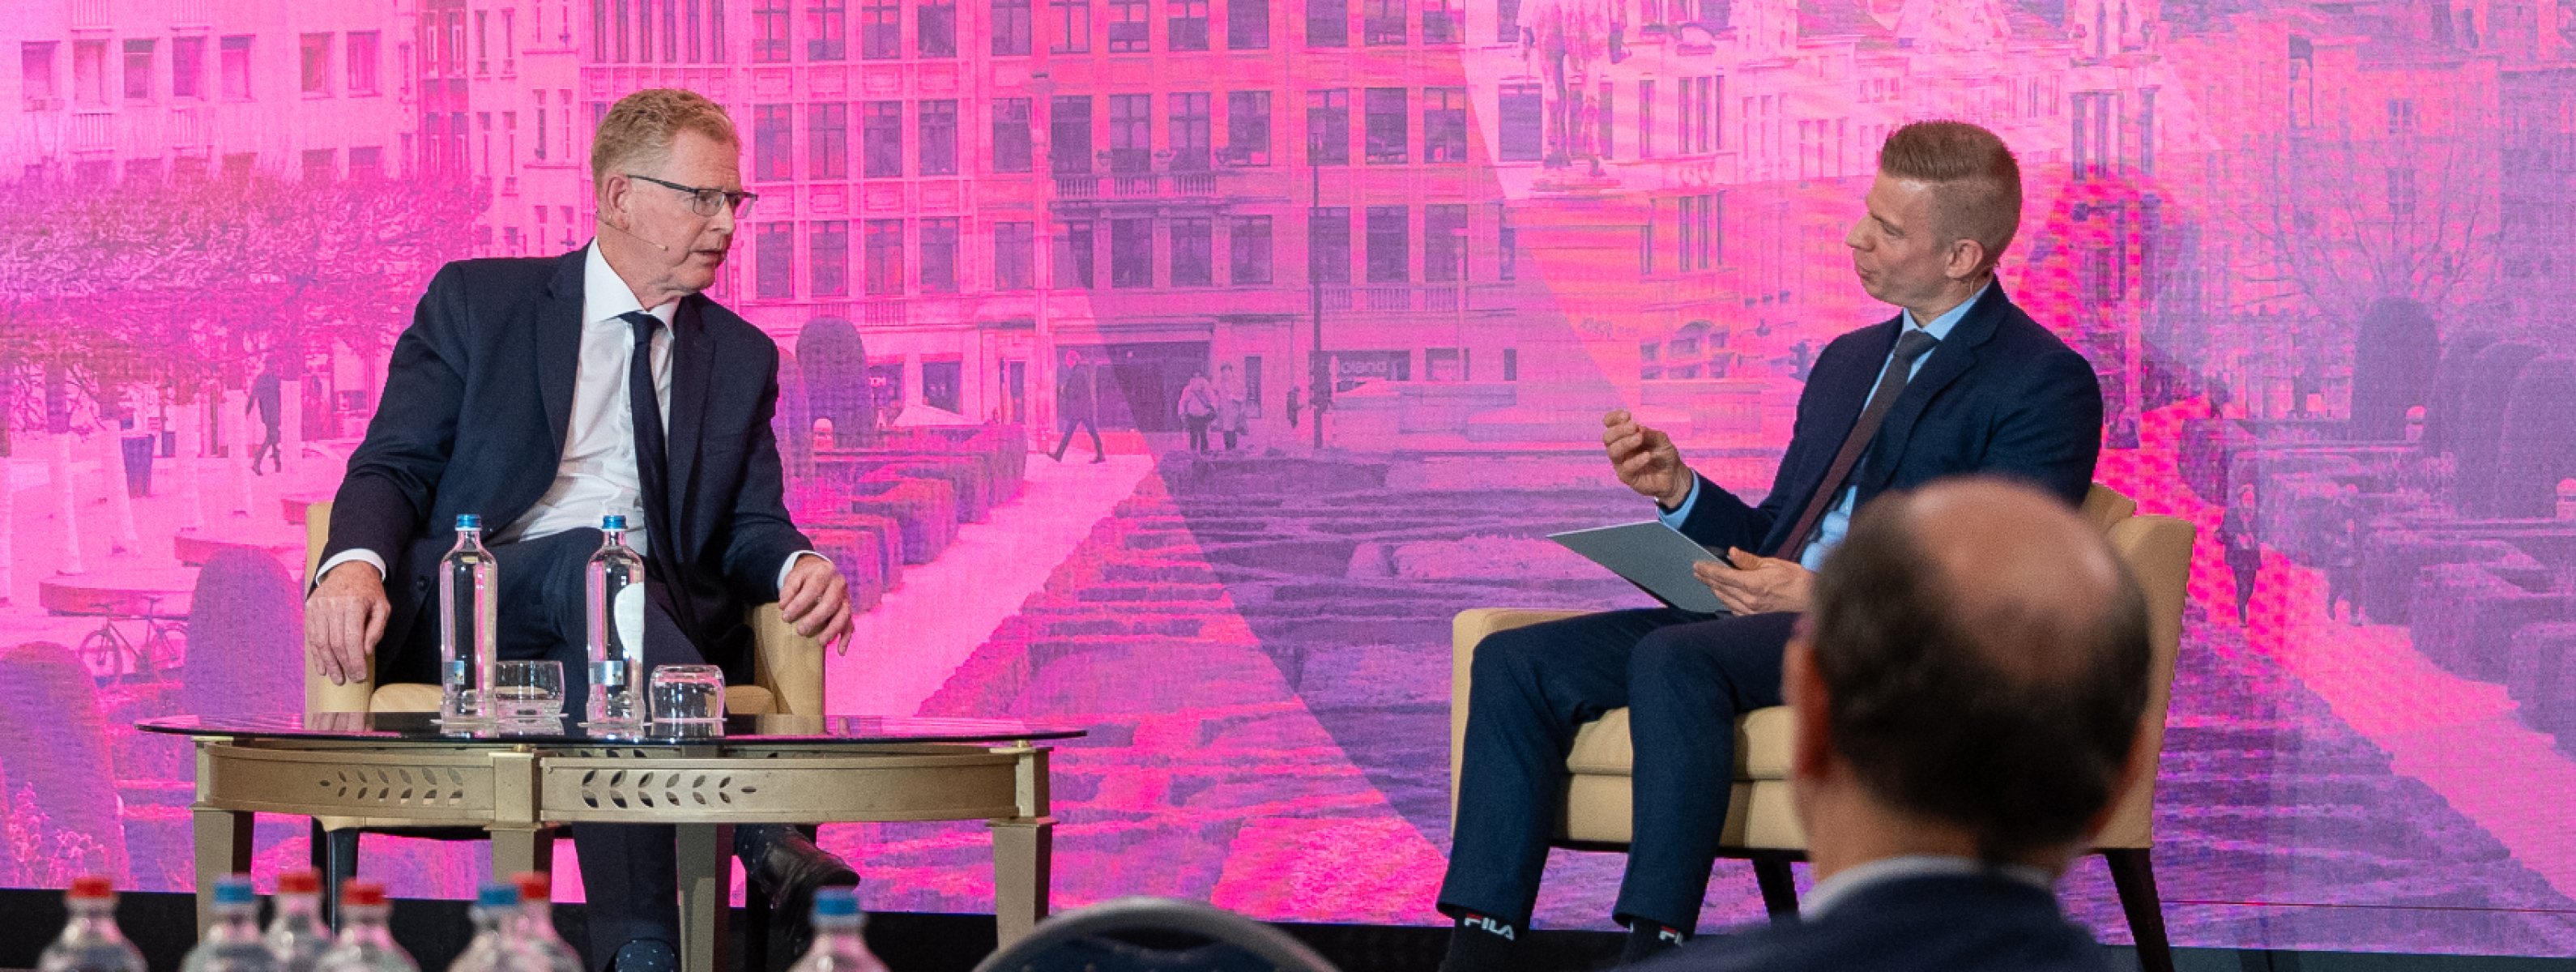 Gerry Cross, Secretary General, IAIS; Dennis Noordhoek, Director of External Stakeholder Engagement, Geneva Association
Governing AI at the speed of innovation
AI has moved rapidly from experimentation to widespread deployment, and increasingly autonomous forms such as agentic AI are raising new governance questions. Participants discussed the difficulty of designing regulatory frameworks for technologies whose capabilities and uses can evolve much faster than legislation.
A recurring theme was that accountability cannot be delegated to technology. Insurers remain responsible for decisions made using AI, including when models or tools are supplied by third parties. Governance therefore needs to evolve alongside adoption, with clear accountability, appropriate human oversight, transparency and the ability to identify and address unfair outcomes.
Rather than a simple choice between more or less regulation, discussions pointed to the value of principles-based approaches and greater alignment between overlapping frameworks and jurisdictions. Effective regulation can also help build the trust needed for AI adoption.
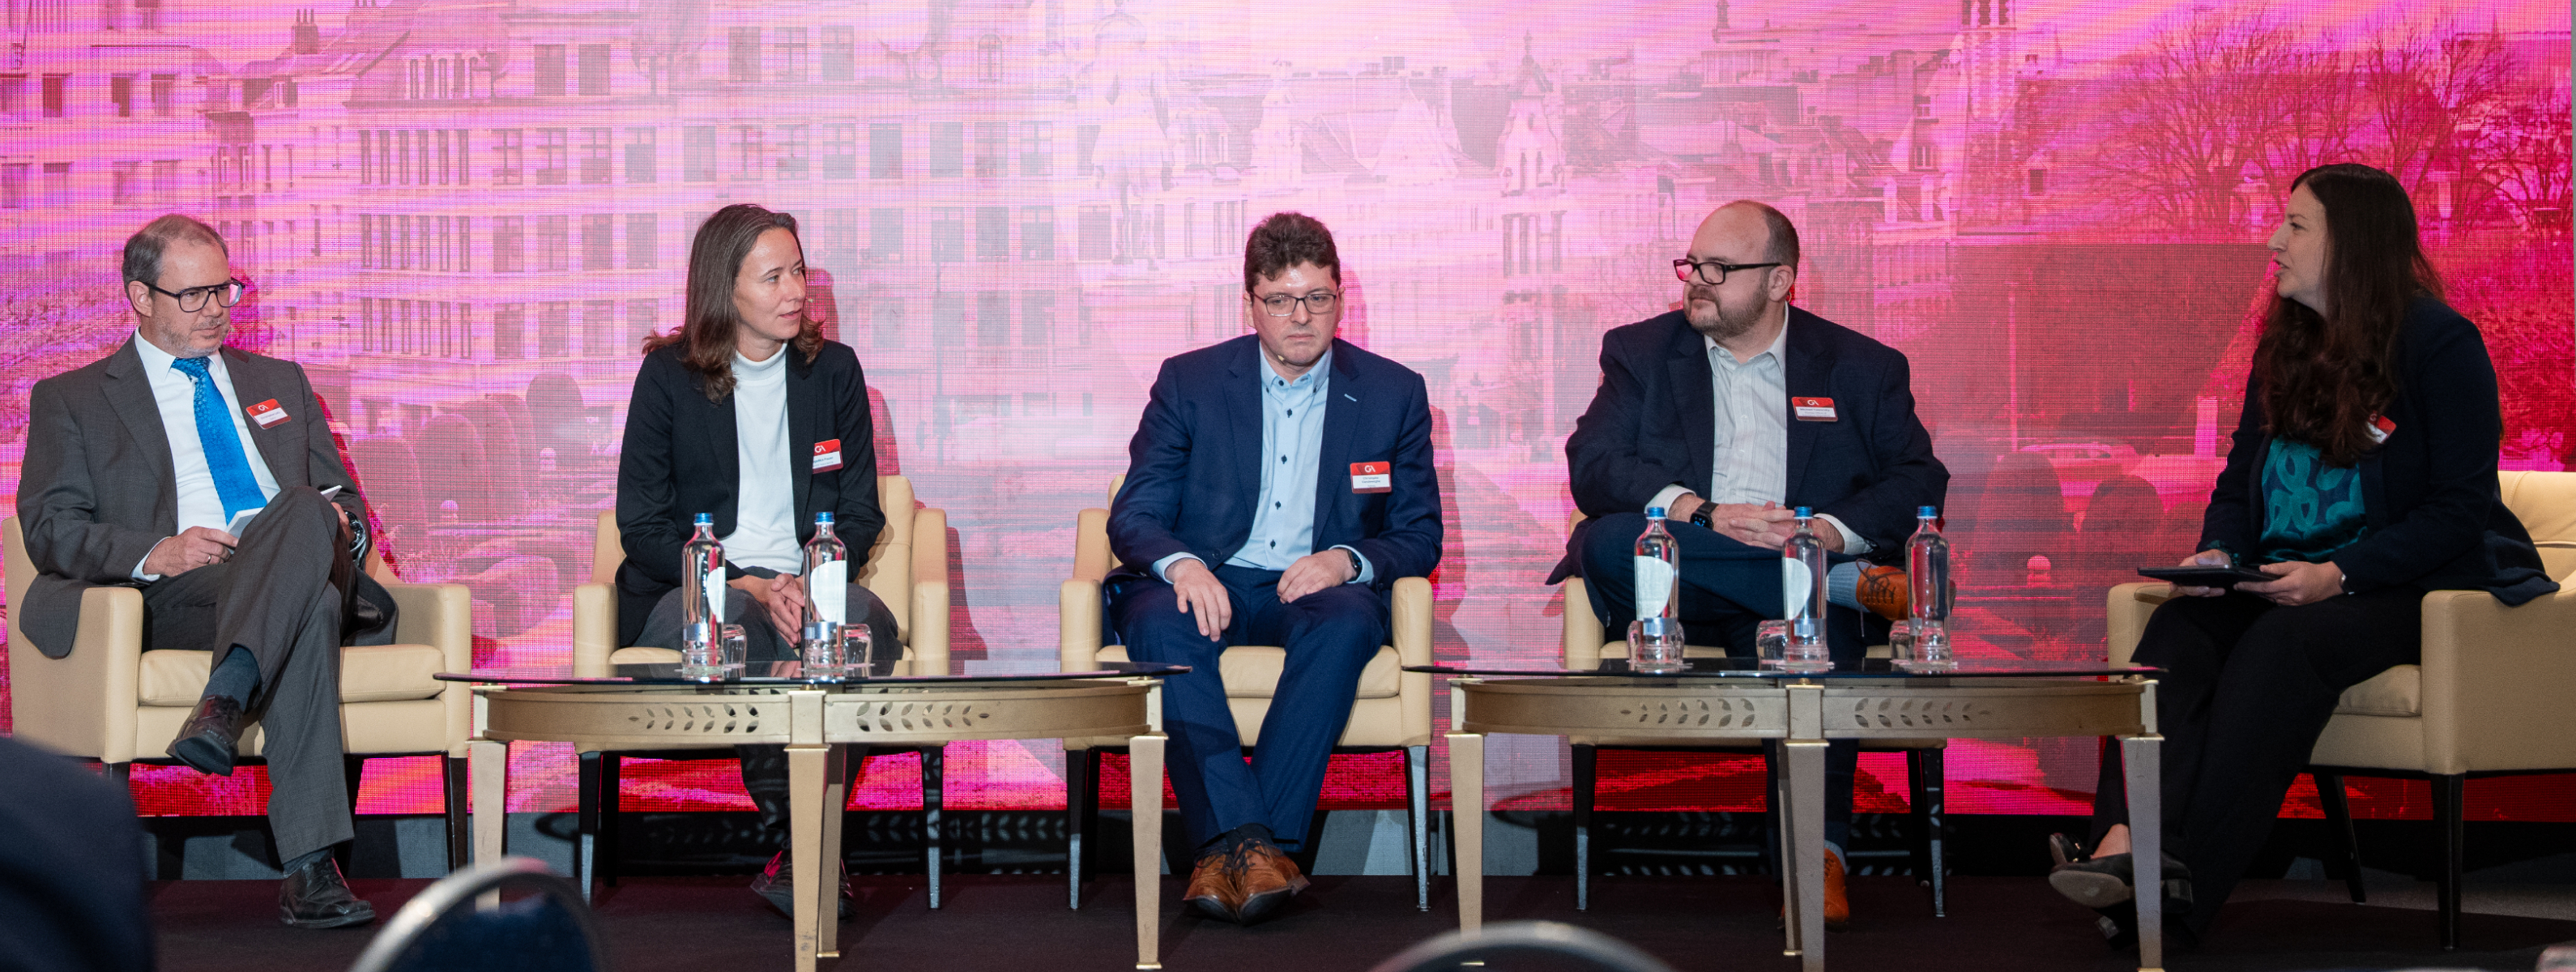 Christopher Lotz, Head of Department, Quantitative Risk Modelling BaFin; Angelika Pauer, Head of Responsible AI, Zurich Insurance; Christophe Vandeweghe, Chief Risk Officer, Ageas; Michael Yaworsky, Commissioner, Florida Office of Insurance Regulation, Chair, NAIC H Committee; Anja Grujovic-Vischer, Director Digital & AI Transformation, Geneva Association
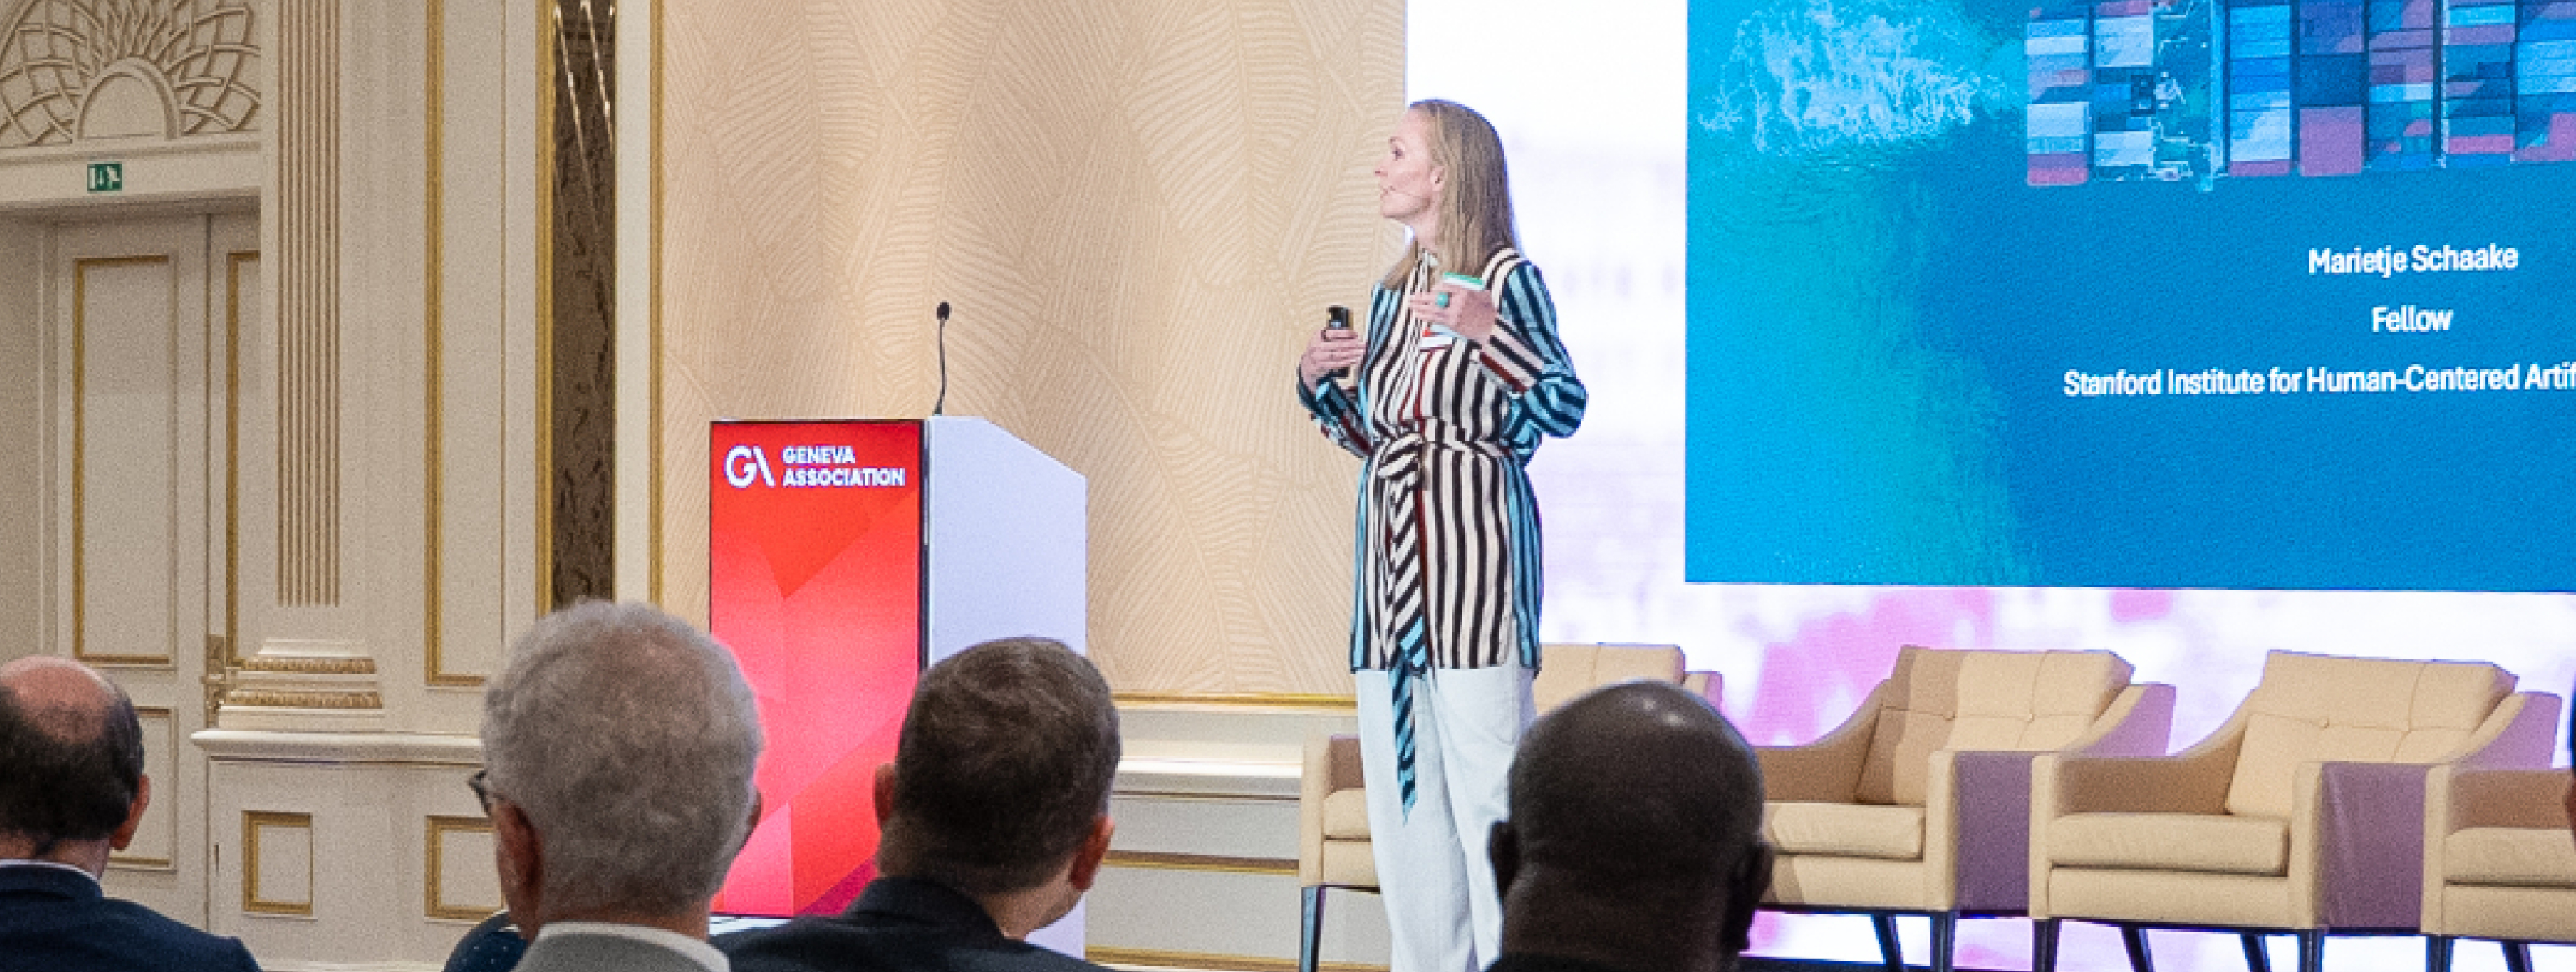 Marietje Schaake, Former Member of the European Parliament and Non-resident Fellow, Stanford Cyber Policy Center and Institute for Human-Centered AI
Turning data into better health outcomes
The potential of health data brought many of these themes together. Better access to interoperable, high-quality data could support research, prevention, more efficient healthcare and better allocation of resources. Europe’s emerging health-data infrastructure provides an important test of how these benefits can be realised across multiple healthcare systems.
The discussion highlighted an important distinction between using large datasets to understand risks and health trends at a population level, and using individuals’ health data to make decisions about them. Better population-level data could help identify disease trajectories, and enable insurers to help with prevention and risk mitigation, while appropriate safeguards are essential to protecting privacy and preventing from data being used for prohibited purposes at the individual level.
Success will depend on implementation as much as regulation: common standards, digital infrastructure and secure environments are necessary, but so too is trust. Patients need confidence that their data is protected and used responsibly, while healthcare providers and other stakeholders need to see tangible value from participating. Clear communication about both the benefits and safeguards will be critical.
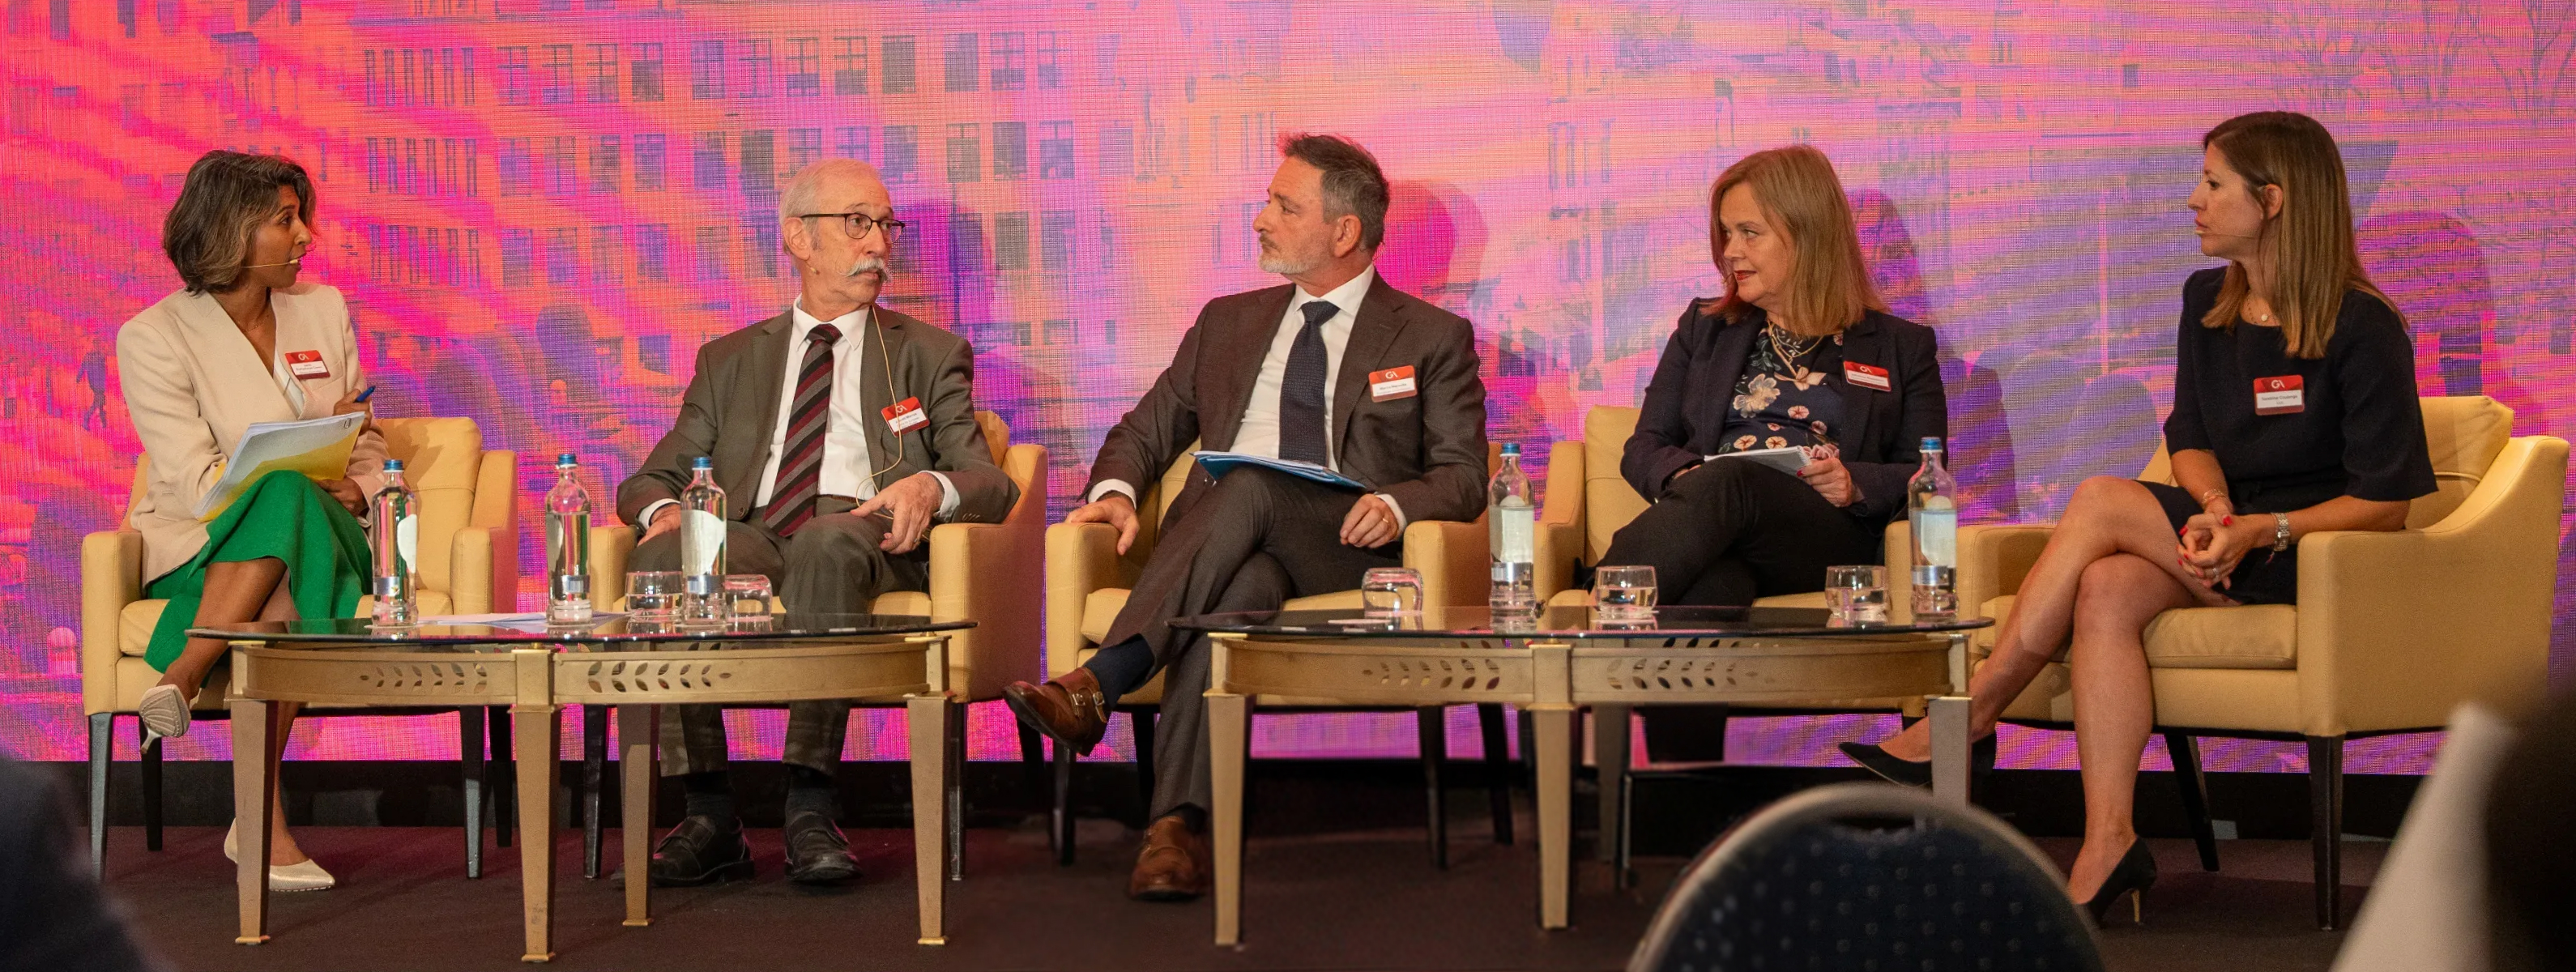 Adrita Bhattacharya-Craven, Director Population Health Trends, Geneva Association; J. Scott Marcus, Associate Senior Research Fellow, Centre for European Policy Studies; Marco Marsella, Deputy Director General, DG SANTE, European Commission; Johanna Seppänen, Director, Information and Development Services, Finnish Medicines Agency; Sandrine Coulange, Global Head of Technical Excellence and Operations, AXA
 Tomislav Sokol, Member of the European Parliament and Committee on Public Health, EHDS Rapporteur
Across these discussions, the overarching message is that regulation is most effective when it does more than control risk. Done well, it can provide the clarity, confidence and conditions that allow insurance to innovate, invest and extend protection as the risks facing society continue to evolve.