Conferences


Each of the three session explores an area in which both legal standards and political choices are highly uncertain and could possibly shift. The first session on the dynamics of social inflation in light of the pandemic investigates the drivers of social inflation and its potential to spread beyond the U.S., with COVID-19 as a potential catalyst. The second session on climate liability risk will shed light on the rise in climate-related litigation in a number of countries. Finally, the third session addresses potential regulatory frameworks for efficiently allocating liabilities related to the use of artificial intelligence.
The Evolving Liability Conference (ELC) is an annual convening of experts from the re/insurance industry, academia and the legal community to discuss the dynamics of liability law, litigation and underwriting and the implications for the re/insurance industry.
The COVID-19 pandemic is likely to accelerate the green and digital transformations of the economy and society, altering the risk landscape for insurers. The Geneva Association’s 2020 Evolving Liability Conference, Liability Trends in a Transitioning World, was held virtually on 6 October 2020 and co-organised with Swiss Re. The conference brought together legal and re/insurance experts to discuss three topics that are representative of such transformations.
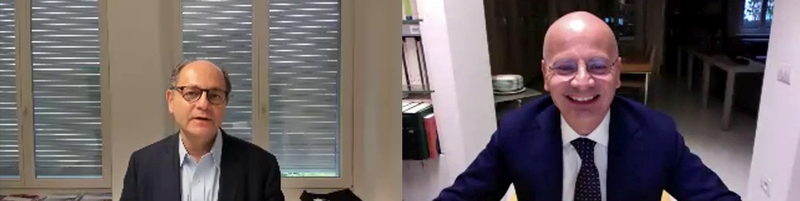
Jad Ariss, Managing Director, The Geneva Association and Pierpaolo Marano, Director Evolving Liability, The Geneva Association welcome participants to the conference.
Session 1 on ʻThe dynamics of social inflation in light of the pandemicʼ investigated the drivers of social inflation and its potential to spread beyond the U.S., with COVID-19 as a potential catalyst.
Top row: Damon Vocke, Partner, Head of Corporate & Regulatory Insurance Litigation, Duane Morris LLP; Darren Pain, Financial Economist, and External Consultant, The Geneva Association; Bottom: Ciara Brady, Global Head of Liability, Allianz Global Corporate & Specialty (bottom).
Key messages
Implications for insurers
Session 2 on ‘Climate litigation risk’ focused on the evolution of the climate litigation landscape and the potential implications for insurers (life and non-life).
Top row: Maryam Golnaraghi, Director Climate Change and Emerging Environmental Topics, The Geneva Association; Jane Mandigo, Senior Expert, Senior Vice-President Property & Casualty Business, Swiss Re; Bottom row: Nigel Brook, Partner, Clyde & Co.
Key messages
Implications for insurers
Session 3 on ‘Artificial intelligence and liability regimes’ addressed potential regulatory frameworks for efficiently allocating liabilities related to the use of artificial intelligence (AI).
Top row: Florian Laeubli, Head NEAT UW Vertical & HUB Underwriting International Casualty, AXA XL; Fabienne Zwagenmakers, Policy Advisor, Public Affairs, Insurance Europe; Bottom row: Angela Gleason, Senior Director, Cyber & Counsel, American Property Casualty Insurance Association (APCIA).
Key messages
Implications for insurers